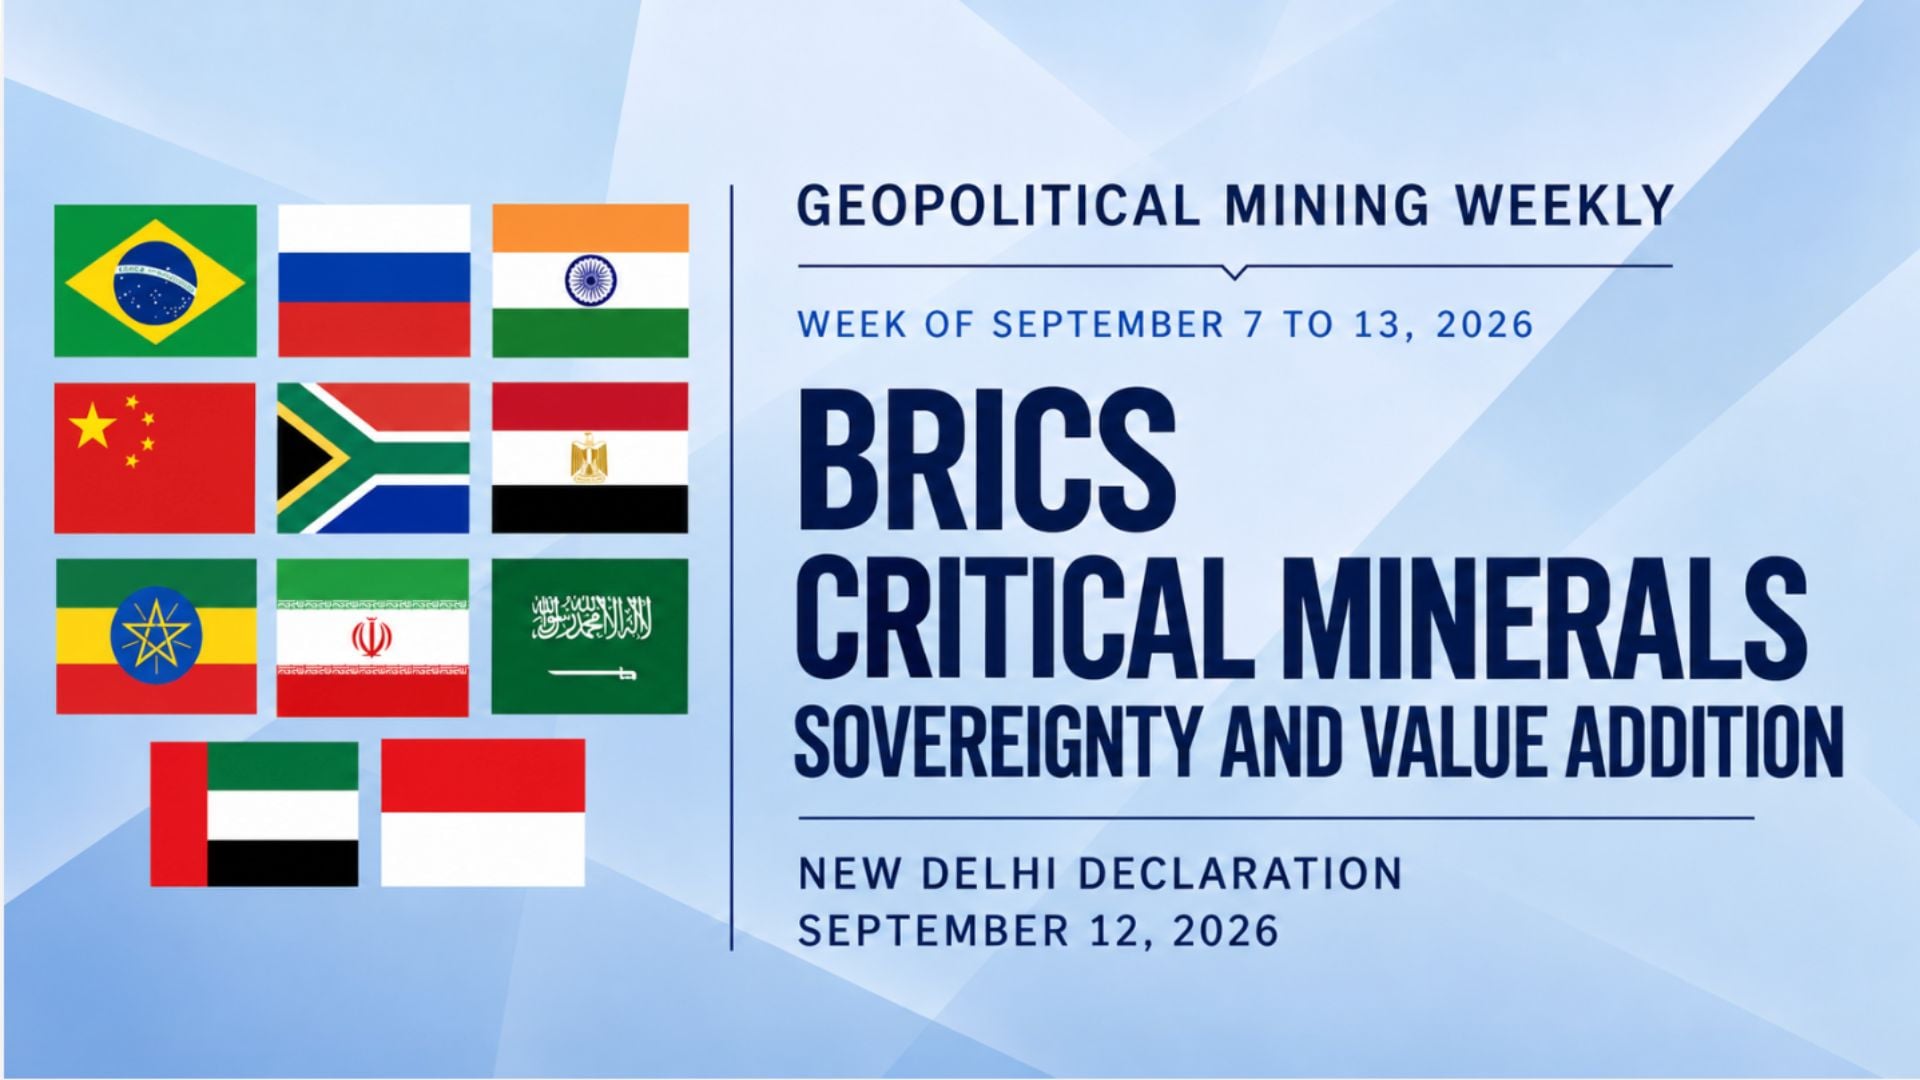
BRICS linked critical mineral supply chains with sovereignty, value addition and benefit sharing. During the same week, the United States and Colombia set a six month project agenda, USA Rare…
Geopolitical Mining Weekly
·
Week of September 7 to 13, 2026
Signals in Motion
·
Sovereignty, Ownership and Project Control
BRICS Critical Minerals Agenda:
Sovereignty, Value Addition and the Terms of Supply
The BRICS New Delhi Declaration linked critical mineral supply chains
with benefit sharing, value addition, economic diversification and
sovereign control over resources. During the same week, the United
States and Colombia signed a six month project framework, USA Rare
Earth broke ground on a US$1.2 billion magnet facility, Indonesia
authorised Weda Bay Nickel to restart and the United States closed
a strategic equity position linked to Trilogy Metals.
By Marta Rivera MuñozEduardo Zamanillo
Evidence base: 5 Daily editions
·
30 verified developments
·
9 Signals active
·
1 additional official multilateral declaration
·
G20 and SCO material used as dated context.
Cover Story · BRICS
BRICS
New Delhi Declaration · September 12
BRICS placed critical minerals inside a wider position on
resilient supply chains, value creation in producing countries,
sovereign rights over resources and energy security.
Critical minerals in the declaration
Resilient supply
The declaration calls for reliable, responsible,
diversified and resilient critical mineral supply chains.
Value addition
Resource rich countries are connected with benefit sharing,
domestic value addition and economic diversification.
Sovereign rights
Countries retain authority over mineral resources
and legitimate public policy measures.
Energy security
Critical minerals are linked with low emission technologies,
energy security and resilient energy supply chains.
Current position
The declaration establishes a political position.
It does not create a common project list, investment vehicle,
procurement mechanism or implementation timetable.
01
Wider multilateral context
BRICS, the G20 and the SCO emphasised
different parts of strategic supply
BRICS · September 12
Sovereignty and value addition
The New Delhi Declaration links resilient critical mineral
supply chains with benefit sharing, economic diversification
and greater value creation in producing countries.
G20 · August 31 to September 1
Functioning value chains and fewer restrictions
The G20 Finance statement identified critical minerals as
essential value chains, urged countries to avoid unnecessary
export restrictions and addressed non market policies.
China objected to the relevant paragraphs.
SCO · Follow up published September 11
Connectivity across Eurasia
The SCO briefing highlighted transport, trade, energy and
digital connectivity. It did not establish a specific critical
minerals instrument, but it addressed the systems through
which Eurasian production and trade may move.
BRICS is counted as an additional official development within this
Weekly. The G20 meeting and the SCO summit took place on August 31
and September 1 and are included only as dated comparative context.
Reading
These forums are not describing one mineral order.
They place different weight on open trade, state sovereignty,
value addition and the infrastructure that connects markets.
What follows
National measures, investment platforms, trade rules
and named projects capable of giving these positions
practical effect.
The week in eight numbers
Project selection, ownership, construction
and production control
Direct evidence
6 months
U.S. Colombia implementation horizon
The framework aims to identify and finance
mining and processing projects within six months.
US$1.2B
USA Rare Earth facility
Groundbreaking completed in South Carolina.
US$35.6M
Trilogy strategic equity
Transaction closed and government ownership created.
4 months
Weda Bay halt
Progressive restart began after Indonesian authorisation.
US$105M
KSK copper sale
Conditions satisfied or waived; legal completion pending.
A$453M
Simberi transaction
Binding agreement with Lingbao, subject to completion.
A$124M
Etango placement
Institutional bookbuild completed before settlement.
What this week says
Five direct readings
01
Governments entered project selection and ownership
The United States and Colombia established a six month
project framework. The United States closed an equity position
linked to Trilogy Metals. JOGMEC entered Brazilian exploration
with future ownership and purchase rights.
02
Authorisation determined whether supply could move
Indonesia reopened Weda Bay. Australia authorised a rare earth
export route to U.S. processing. Traditional Owner consent
advanced Winu, while cultural and regulatory approvals allowed
Molyhil drilling to proceed.
03
Downstream capacity became physical
USA Rare Earth began site work, Finniss produced first
concentrate, Cuiú Cuiú poured first gold and
Neves placed most of its direct capital scope under contract.
04
Ownership and offtake reorganised future supply
KSK, Simberi and Etango moved through sale, financing
and offtake structures involving Chinese buyers or state linked
capital, while Australian concentrate was connected with
U.S. processing.
05
Safety and consent remained operating conditions
Tulu Kapi suspended development after a fatal security incident.
Winu advanced through Nyangumarta consent, and Molyhil secured
cultural heritage clearance before planned drilling.
Weekly reading:
governments and state linked institutions made concrete decisions
about who may own, finance, export, restart and process strategic
minerals. The instruments carry different legal and operating weight,
from political declarations and award negotiations to closed equity,
signed agreements, physical construction and first production.
02
Project selection and state capital
Public involvement took four distinct legal forms
United States and Colombia6 months
Bilateral project framework
Guarantees, loans, equity, insurance, offtake,
price mechanisms, permitting and ownership review
are included. No project or budget has yet been named.
United States and Trilogy MetalsUS$35.6M
Strategic equity closed
The U.S. Government became an approximately 10%
shareholder. Proceeds are committed to Ambler Metals.
Japan and AclaraUS$4.5M
Exploration earn in
JOGMEC may fund exploration, earn 30% in one project
and secure purchase rights linked to future production.
United States DOEUS$73M
Mine testbeds selected
Four projects entered award negotiations.
Final awards and funding obligations remain pending.
Reading
Public policy reached projects through a signed bilateral
framework, actual share ownership, an exploration earn in
and proposed research funding. These instruments should not
be treated as equivalent commitments.
What follows
Named U.S. Colombia projects, Arctic permitting and access,
selection of the JOGMEC project and completed DOE awards.
03
Authorisation and consent
Public decisions and rights holder agreements
opened or limited access to supply
Asset
Decision
Position this week
Next stage
Weda Bay Nickel
Indonesia
Restart authorised
Progressive restart began after four months of
Care & Maintenance.
Remobilisation, revised production volumes,
grade visibility and stable operations.
Donald rare earths
Australia and United States
Export licence granted
Australia opened a legal route for concentrate
to reach Energy Fuels processing in Utah.
Project finance, final investment decision,
construction and permit renewal when required.
Winu
Western Australia
Project Agreement signed
Nyangumarta consent now informs planning,
heritage protection and participation.
Regulatory approvals, technical definition,
capital approval and final investment decision.
Molyhil
Northern Territory
Drilling approvals secured
Regulatory and Sacred Site clearances allow
development drilling to be mobilised.
Drilling results, Pre Feasibility Study,
environmental approvals and project finance.
Macraes Phase 4
New Zealand
Application lodged
Fast Track review has begun for a proposed
mine life extension.
Permit decision, ancillary approvals,
technical review and capital commitment.
Reading
Geology and finance did not determine access on their own.
Production, export, drilling and project planning all depended
on authorisation, consent or formal review.
What follows
Normalised Weda Bay production, Donald financing,
Winu approvals, Molyhil drilling and a Macraes permit decision.
04
Construction and first output
Plants and projects crossed visible physical milestones
Asset
Stage
Evidence this week
Next stage
USA Rare Earth
South Carolina
Groundbreaking
Site development began for an approximately
US$1.2 billion metal and magnet facility.
Construction, equipment installation,
customer qualification and 2028 commissioning.
Finniss
Northern Territory Australia
First concentrate
Recommissioned plant produced its first
spodumene concentrate after the staged restart.
Plant stability, recovery, throughput,
product quality and first commercial shipment.
Youanmi
Western Australia
Major construction
Plant foundations, underground development,
camp expansion and equipment deliveries advanced.
Stoping, installation, commissioning
and first gold targeted for mid 2027.
Neves
Brazil
CAPEX contracted
About 71% of direct DFS capital is supported
by contracts and firm agreements.
Mobilisation, physical installation,
remaining procurement and commissioning.
Cuiú Cuiú
Brazil
First gold poured
Approximately 1,130 ounces were produced
during wet circuit commissioning.
Completion of commissioning,
stable recovery and commercial production.
Watershed
Queensland
Early works
Primary approvals are in place and access,
clearing and site preparation have begun.
Engineering, financing,
final investment decision and construction.
Reading
This week contained real physical evidence:
ground was broken, concentrate and gold were produced,
foundations advanced and contracts moved into mobilisation.
What follows
Repeatable output, commercial shipment,
schedule control, customer acceptance and completed commissioning.
05
Ownership and market routes
Transactions connected mineral assets
with new strategic buyers
Indonesia · KSKUS$105M
Sale conditions cleared
Norin is positioned to acquire the project.
Legal completion and payment remain pending.
Papua New Guinea · SimberiA$453M
Binding control transaction
Lingbao agreed to acquire St Barbara’s remaining
interest, while St Barbara retains future royalties.
Namibia · EtangoA$124M
Placement bookbuild completed
The broader CNOL structure may provide up to
US$321.5 million and purchase 60% of future output.
Brazil · Aclara and JOGMEC30%
Future project interest
JOGMEC may earn a project interest and secure
purchase rights after funding exploration.
The structures are different. KSK and Simberi are proposed asset sales.
Etango combines equity, project finance and offtake.
The Aclara venture begins at exploration and may later create
ownership and purchasing rights.
Reading
Control over future supply is being negotiated before production,
through ownership transfers, state linked capital and contracted
access to output.
What follows
KSK and Simberi completion, Etango settlement and financing,
project selection under the JOGMEC venture and eventual development decisions.
06
Safety, consent and legitimacy
Human security and territorial authority
remained part of project execution
STOPPEDTulu Kapi development · Ethiopia
Development was suspended after a fatal security incident
KEFI reported multiple fatalities involving security personnel
and community members, including one employee. Physical work
and further financing deployment were suspended while the company,
public authorities and community representatives assess the conditions
required for a safe return. The available disclosure does not support
conclusions about the cause of the incident.
Winu · Australia
Consent entered project planning
The Nyangumarta Project Agreement covers cultural heritage,
environmental impacts, training, employment and business participation.
Molyhil · Australia
Sacred Site clearance secured
The clearance allows development drilling to proceed.
It is not a mine approval or investment decision.
Barroso · Portugal
Local monitoring added to preconstruction
Final drilling, lender review and a local consultative structure
are advancing before construction and remaining approvals.
Reading
The week showed both interruption and constructive agreement.
Safety failures can stop an already financed development,
while consent and heritage processes can create a basis for work to proceed.
What follows
A safe and credible Tulu Kapi pathway,
Winu approvals and investment decisions,
Molyhil drilling and continued local oversight at Barroso.
Mining viability across the week
Political direction, legal instruments and physical work
advanced at different speeds
The week ranged from a multilateral declaration to closed equity,
construction, first output, ownership agreements and a security suspension.
Multilateral position
Adopted
BRICS linked critical mineral supply with sovereignty,
value addition and benefit sharing.
Bilateral project architecture
Signed
The U.S. Colombia framework provides tools and a six month horizon,
while named projects and committed capital remain ahead.
State ownership
Closed
The U.S. Government became an approximately 10% Trilogy shareholder.
Downstream construction
Active
USA Rare Earth broke ground and Neves placed most direct capital scope under contract.
Production authorisation
Restored
Weda Bay began a progressive restart, while 2026 volumes and grades remain uncertain.
Ownership transfers
Advancing
KSK and Simberi have moved close to completion but have not yet changed legal ownership.
Consent and safety
Uneven
Winu and Molyhil advanced through formal agreements and clearances,
while Tulu Kapi remained suspended after loss of life.
Durable supply
Still forming
Several projects crossed real thresholds, while stable production,
customer approval, financing and completion remain uneven.
Weekly conclusion:
the week added legal authority, ownership, construction and first output.
Their strategic value will be determined by stable production,
accepted products and institutions capable of sustaining the projects.
Dates and decisions to watch
Known next stages
Weekly calendar
Timing
Item
Next stage
Near term
KSK copper sale
Formal completion, transfer of Indokal and receipt of the US$105 million consideration.
September 15 to 16
Etango placement
Settlement and allotment, followed by completion of the wider CNOL financing structure.
Within six months
U.S. Colombia framework
Named mining and processing projects, participating agencies and binding financial instruments.
2026
Weda Bay Nickel
Revised production visibility, grade performance and evidence of normalised operations.
2026 to 2027
Trilogy and Arctic
Mine permitting, Ambler Access Project progress and further financing support.
2027
Uberaba and Kasiya
Pre Feasibility work, resource definition and pilot evidence for rare earth recovery.
2028
USA Rare Earth
Planned commissioning of the Blacksburg metal and magnet facility.
Before resumption
Tulu Kapi
Measures agreed with communities and public authorities for a safe operating environment.
The BRICS declaration is the additional current week development.
G20 and SCO documents are included as dated context.
The five Daily editions contain the full source trail for the
thirty project and policy developments reviewed.
Signals for 2026 provides the observation framework.
The Daily records new developments and their stage.
The Weekly compares the full evidence, distinguishes the legal
and operating weight of each instrument and identifies the
conditions that still shape durable supply.