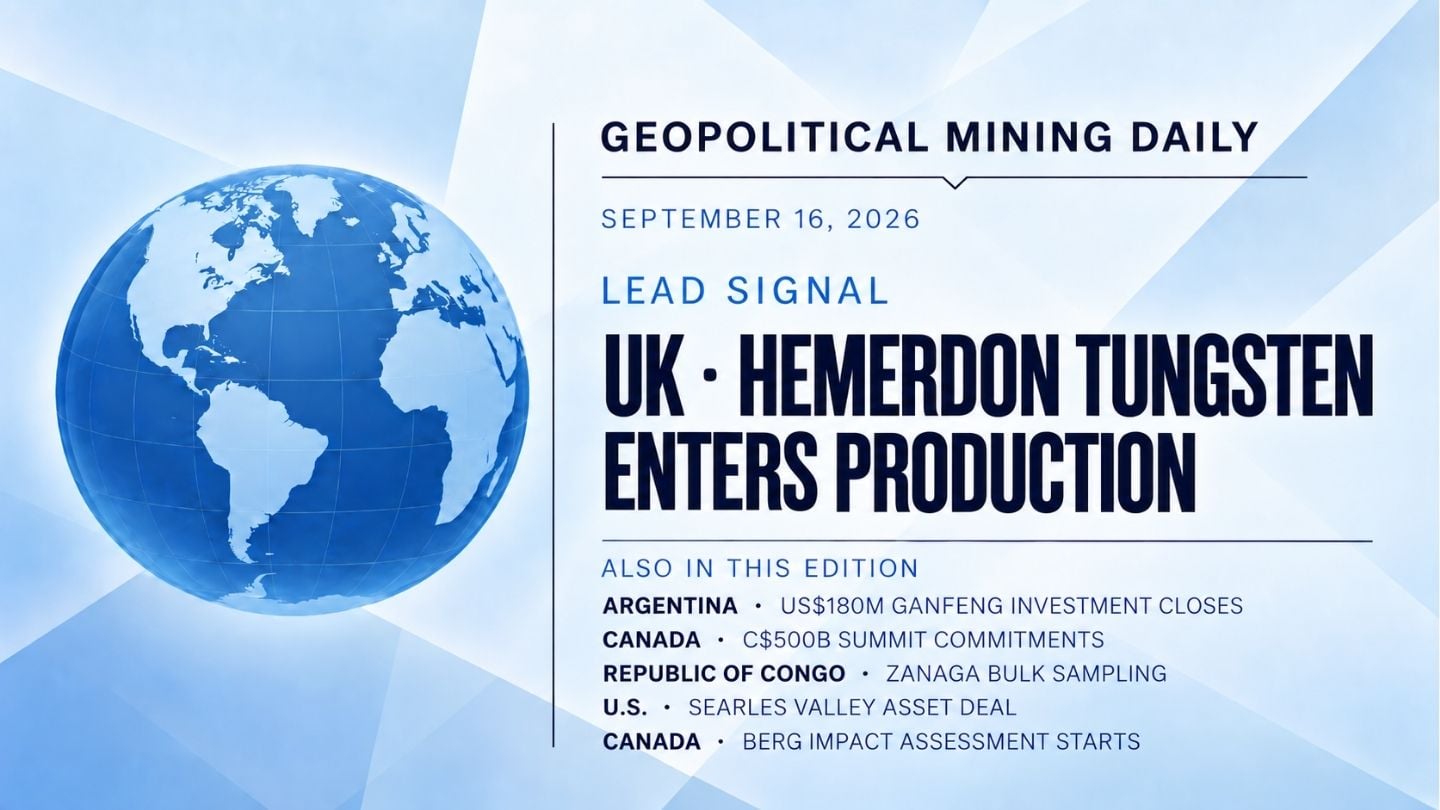
Geopolitical Mining Daily · September 16, 2026
UK Hemerdon Tungsten Mine Enters Production
Hemerdon has entered production in the United Kingdom, with tungsten and tin ore now passing through the processing plant as the state backed restart moves into operational ramp up. Argentina closes strategic lithium capital, Canada converts its Investment Summit into economy wide commitments and new mining tax treatment, the Republic of Congo advances iron ore pilot work, a United States boron platform moves toward a change of control, and Berg Copper enters formal impact assessment planning in Canada.
Tungsten West announced that Hemerdon has entered production and that ore is now being processed as the mine begins its next ramp up phase. Lithium Argentina closed a US$180 million strategic investment from Ganfeng through a six year convertible note. The Government of Canada said the Canada Investment Summit resulted in nearly C$500 billion of new investment commitments and announced a Productivity Mega Deduction that includes mining property. Zanaga launched bulk sampling for pilot scale validation of its revised direct reduced iron flowsheet in the Republic of Congo. 5E Advanced Materials signed a definitive agreement to acquire operating Searles Valley critical mineral assets in California, subject to court and other approvals. Canada’s Impact Assessment Agency accepted the initial project description for Berg Copper and moved the project into the planning phase of federal impact assessment.
The 2026 observation framework
The ten Signals for 2026
Every Daily edition is read against the same ten strategic lenses. Signals activated by today’s verified developments are highlighted below.
Today’s direction of travel
Execution is becoming easier to distinguish from intention. Hemerdon is processing ore after a state backed restart. Lithium Argentina has closed strategic capital rather than merely announcing it. Canada has moved from an investment prospectus to broad capital commitments and new tax treatment. Zanaga has mobilised field work to validate a processing route. 5E has signed for operating assets but still needs closing approvals. Berg has entered formal assessment planning, not received project approval.
Lead development
Hemerdon tungsten and tin mine enters production in the United Kingdom
What happened
On September 15, Tungsten West announced that the Hemerdon tungsten and tin mine in Devon had entered production, with ore being processed through the plant as the company begins the next phase of operational ramp up. The company said operations will now be progressively increased toward targeted steady state production.
The milestone follows the United Kingdom National Wealth Fund investment announced in August to support the restart of Hemerdon. The September update is therefore a change in physical status rather than another financing announcement: the asset has moved from restart construction and commissioning into ore processing and production ramp up.
Tungsten West continues to describe Hemerdon as one of the world’s largest known tungsten deposits and as a potential long term source of tungsten concentrate for the United Kingdom and international partners. Entry into production does not yet demonstrate steady state throughput, recovery, concentrate quality, unit costs or sustained commercial shipments. Those operating metrics now become the next test.
Signal reading
Hemerdon provides a direct example of strategic mineral policy crossing into physical output. Public capital helped move a dormant Western tungsten asset toward restart, and the plant is now processing ore. The strategic value will be established only if ramp up converts that milestone into repeatable tungsten concentrate production at acceptable recovery, quality and cost.
Next proof point: sustained plant throughput, tungsten and tin recoveries, concentrate specifications, operating costs, first repeatable commercial shipments and progress toward targeted steady state production.
Primary exchange announcement
Tungsten West RNS: Hemerdon enters production and begins ore processing.Major development
Lithium Argentina closes US$180 million strategic investment from Ganfeng
What happened
Lithium Argentina closed the previously announced US$180 million strategic investment from Ganfeng Lithium through issuance of a six year unsecured convertible note. The note bears a 4.0% annual coupon, matures six years from issuance and is convertible into Lithium Argentina common shares at US$12.50 per share.
The company said the net proceeds, together with cash on hand, will be used to repay in full US$259 million of convertible notes due in January 2027. Management said the resulting balance sheet gives it greater flexibility to advance Stage 2 at Cauchari Olaroz and support the Pozuelos Pastos Grandes project through a phased development approach.
Ganfeng currently owns approximately 9.6% of Lithium Argentina’s issued shares. If the note were fully converted, Ganfeng would receive 14.4 million additional shares and would own approximately 16.1% on a fully diluted basis. The companies’ PPG joint venture remains expected to close by the end of September 2026.
Signal reading
The strategic relevance lies in the transaction moving from announced capital to closed capital and in the deeper financial relationship with an existing Chinese operating partner. The new note improves the maturity profile and reduces near term refinancing pressure, while potentially increasing Ganfeng’s ownership position if converted. Project advancement still depends on investment decisions, permits, construction and operating execution at Stage 2 and PPG.
Next proof point: repayment of the January 2027 convertible notes, completion of the PPG joint venture, formal Stage 2 and PPG development decisions, defined capital programs and evidence that the stronger balance sheet converts into additional operating capacity.
Policy and capital development
Canada closes Investment Summit with nearly C$500 billion in new commitments
What happened
The Prime Minister’s Office said the first Canada Investment Summit concluded with nearly C$500 billion in new investment commitments to Canada. The figure is economy wide rather than mining specific. The government reported nearly C$100 billion of new capital commitments from pension funds, insurers and institutional investors and nearly C$325 billion in new bank financing for Canadian businesses and infrastructure.
Mining and critical minerals are explicitly present inside that financial architecture. TD committed C$150 billion over five years across sectors including critical minerals and resources, while BMO said it would invest and mobilise C$70 billion over ten years across sectors including mining and critical minerals. The government also highlighted approximately C$140 million of Canada Growth Fund support for Generation Mining’s Marathon copper and palladium project.
Prime Minister Mark Carney also announced a Productivity Mega Deduction that expands the categories of assets eligible for immediate expensing from roughly 15% to more than 65%, including mining property. The government estimates that the marginal effective tax rate on new business investment will fall from roughly 13% to 6.4%. Those measures change tax treatment and financing capacity, but do not allocate the nearly C$500 billion total specifically to mining or guarantee that individual projects will reach investment decisions.
Signal reading
The September 14 Daily captured Canada’s project pipeline at the start of the Summit. The closing evidence moves the story to the next layer: large pools of capital have announced commitments, banks have identified critical minerals and mining within their financing mandates, and mining property has been included in a broader immediate expensing framework. The strategic test now moves from national mobilisation to project level conversion.
Next proof point: identification of mining projects receiving financing mandates, binding debt or equity, use of the new tax treatment in project economics, capital drawdowns, Final Investment Decisions and construction starts linked to the Summit pipeline.
Major development
Zanaga launches bulk sampling to validate its revised DRI iron ore flowsheet
What happened
Zanaga Iron Ore Company launched a bulk sampling program at its Zanaga Iron Ore Project in the Republic of Congo. Approximately 30,000 tonnes of ore are being extracted to assemble a 100 tonne composite sample from the hematite zone targeted for Stage 1 operations of 12 million tonnes a year.
The composite material will be used for metallurgical testing and pilot scale validation of Zanaga’s revised direct reduced iron processing flowsheet. The program is also intended to generate enough concentrate for product specification work, process engineering design and testing with steel mill customers, independent laboratories and potential offtakers.
Zanaga said the program represents the first major equipment mobilisation at the project since 2014. Excavation is proceeding under environmental and mining permits after state and community consultation. The work is intended to support completion of front end engineering design and a future Final Investment Decision. Bulk sampling is therefore a technical development step, not a construction decision.
Signal reading
Zanaga is moving from study assumptions into larger scale physical validation of the processing route and product specification required for low carbon steel markets. The strategic value of a large high grade iron ore resource depends on whether it can consistently produce the DRI specification concentrate targeted by customers. This program begins to test that interface at a scale relevant to process design and commercial qualification.
Next proof point: completion of the 100 tonne composite sample, pilot scale metallurgical results, concentrate specifications, steel mill and offtaker testing, FEED completion, updated capital and operating estimates and a financeable path to FID.
Primary exchange announcement
Zanaga Iron Ore Company RNS: bulk sampling program, DRI pilot work and FEED objectives.Control and industrial development
5E signs definitive agreement for Searles Valley critical mineral assets
What happened
5E Advanced Materials was selected as the successful bidder and signed a definitive agreement to acquire specified operating assets of Searles Valley Minerals through a court supervised Section 363 bankruptcy sale. The assets include critical mineral production facilities, brine resources and associated infrastructure in San Bernardino County, California.
Consideration consists of approximately US$3.4 million in cash, 8.3 million 5E common shares and an approximately US$6.2 million senior unsecured promissory note from a company subsidiary. The asset package includes processing facilities, on site cogeneration, the Trona Railway connection to the national rail network and logistics infrastructure serving West Coast export routes.
The transaction is expected to close in early October 2026 and remains subject to Bankruptcy Court approval, Surface Transportation Board authorization for railway assets, receipt of US$10 million in senior secured bridge financing and other customary conditions. Searles Valley operations are expected to continue during the process. A signed purchase agreement therefore establishes the proposed transfer structure, but ownership has not yet changed.
Signal reading
If completed, the transaction would connect operating borate production, brine resources and established rail and processing infrastructure with 5E’s longer term Fort Cady development platform. The strategic importance is the potential consolidation of operating and future United States boron capacity under one domestic company. The immediate proof point, however, is still transaction completion rather than integration or increased production.
Next proof point: Bankruptcy Court approval, Surface Transportation Board authorization, funding of the US$10 million bridge facility, early October closing, continuity of operations and a defined integration and capital plan for Searles Valley and Fort Cady.
Primary company distribution
5E Advanced Materials: definitive Searles Valley asset purchase agreement and closing conditions.Regulatory development
Berg Copper enters federal impact assessment planning in British Columbia
What happened
On September 15, the Impact Assessment Agency of Canada accepted the initial project description for Surge Copper’s proposed Berg Copper Project in British Columbia. The federal assessment is now listed as in progress and in the Planning Phase. The Agency said it will announce a joint public comment period with British Columbia’s Environmental Assessment Office at a later date.
Berg is proposed as a new open pit copper and molybdenum mine approximately 80 kilometres southwest of Houston, British Columbia. The current project description includes an open pit, workforce accommodation, processing and mine waste management facilities and approximately 125 kilometres of new transmission line connecting to BC Hydro at the Telkwa substation.
The proposed operation would process approximately 43 million tonnes of ore a year, equivalent to about 120,000 tonnes a day, over a planned 33 year mine life. Acceptance of the initial project description starts the federal assessment planning process. It is not an environmental approval, a construction permit or an investment decision.
Signal reading
Berg has moved from company project definition into a formal federal regulatory pathway. That matters because future copper supply depends on the ability to convert a large technical concept into a project that can satisfy environmental assessment, infrastructure, consultation, engineering and financing requirements. The regulatory clock has started, but the project remains at an early assessment stage.
Next proof point: the joint federal and provincial comment period, assessment requirements, Indigenous and public engagement, environmental studies, project design refinement, subsequent permitting milestones and a financeable development plan.
Direct federal regulatory source
Impact Assessment Agency of Canada: Berg Copper Project status, proposed scale and Planning Phase start.The system reading
What today’s evidence tells us
The strongest signal today is the difference between successive execution stages. Hemerdon is already processing ore, although stable production still has to be demonstrated. Lithium Argentina has closed strategic capital and changed its balance sheet, but future expansion decisions remain ahead. Canada has announced almost C$500 billion in economy wide investment commitments and broader immediate expensing that includes mining property, but those numbers must still convert into project level finance. Zanaga has mobilised bulk sampling and pilot work, not mine construction. 5E has signed a definitive asset agreement, but court and railway approvals still separate it from ownership. Berg has entered federal assessment planning, which starts a regulatory process rather than completing it. Across all six developments, the strategic distinction is becoming sharper: policy, capital, contracts, permits, commissioning and production are separate thresholds, and durable supply exists only after enough of them converge.
Signals for 2026 gives the map. The Daily records new evidence against that map. Today’s lead follows Hemerdon from state backed restart finance into physical ore processing, while the wider edition tracks closed strategic capital, national investment mobilisation, process validation, asset control and regulatory entry across five additional developments.