Geopolitical Mining Daily · October 21, 2026
Phoenix Tailings Selects Rochester for Rare Earth Separation
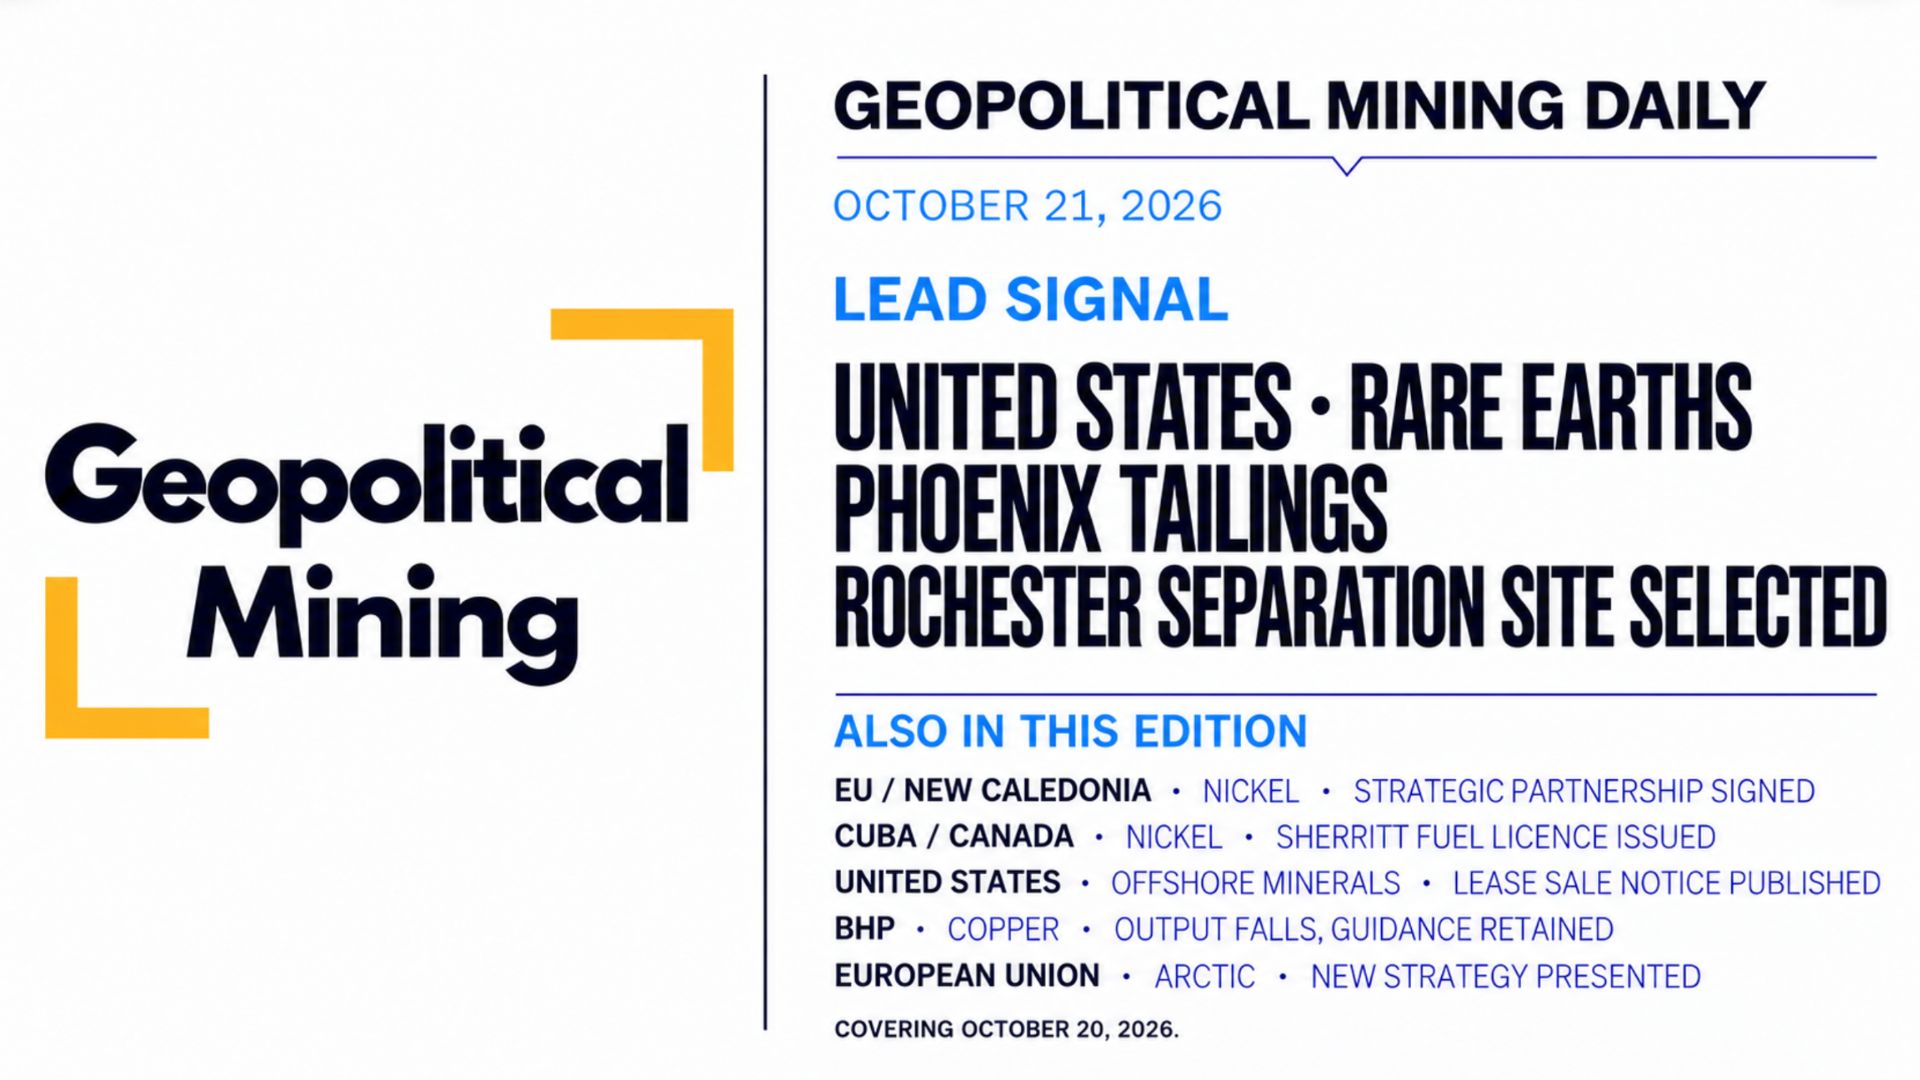
Phoenix Tailings selects Rochester for rare earth separation, leading this Geopolitical Mining Daily for senior executives, investors and policymakers. Six developments reported on October 20 connect processing capacity, strategic partnerships, sanctions, mineral rights and operating performance.
A US separation project, a European nickel partnership and a limited Cuban fuel licence show how industrial supply depends on capital, permissions and execution.
Processing plans gain a location in Rochester, while Europe builds a nickel partnership with New Caledonia. Sherritt secures permission for essential inputs but still faces restart and financing conditions. Meanwhile, US offshore leasing and Europe’s Arctic strategy reveal different approaches to resource access. BHP’s copper results bring the focus back to physical delivery. Each stage changes the investment case in a different way.
The GM observation framework
The ten Signals
Each Daily uses the same ten strategic lenses. The highlighted dimensions classify the developments in this edition.
United States · Rare earth processing
Phoenix Tailings Selects Rochester for Rare Earth Separation
What happened
Phoenix Tailings selected Eastman Business Park in Rochester for its Freedom Separation facility on October 20. The plant forms part of the company’s broader US$1.2 billion plus Freedom Project, which combines separation with downstream metal production. Planned annual capacity exceeds 18,000 tons of mixed feedstock and 4,400 tons of separated rare earth oxides.
The company targets a production ramp in 2027 and full production in 2028. Meanwhile, the Office of Strategic Capital’s US$500 million loan commitment remains conditional. Feedstock can come from mined and recycled sources. The selected site therefore advances a planned processing chain, while financing completion, construction and commissioning remain material execution stages.
For investors, the strategic value lies in connecting feedstock to usable industrial material within a domestic chain. However, oxide output still requires downstream conversion before reaching magnet customers. The next tests are reliable inputs, financing closure and qualification of saleable products. Site infrastructure and experienced workers can support delivery, but the announced capacity should remain outside current supply balances.
European Union / New Caledonia · Nickel and cobalt
EU and New Caledonia Sign a Strategic Raw Materials Partnership
What happened
The European Union and New Caledonia signed a strategic partnership on sustainable raw materials in Nouméa on October 20. The agreement covers closer integration of mineral value chains, investment, infrastructure, skills and research. Energy and transport feature alongside responsible production and greater local value creation.
The signed memorandum envisages an implementation roadmap within six months. It also explicitly creates no financing commitment or obligations under domestic or international law. Consequently, the partnership establishes a framework for developing projects rather than a funded construction programme or a binding purchase agreement.
For nickel producers, the commercial opportunity depends on converting political alignment into affordable power, credible capital and customers. European diversification can support that process, while New Caledonia’s industrial needs make infrastructure economics central to any investment case. Boards should watch the roadmap for named projects, responsible institutions and financing instruments. Those details will show whether the partnership can improve operating competitiveness and durable access to markets.
Cuba / Canada · Nickel and sanctions
Sherritt Receives a Fuel Licence as Moa Restart Conditions Remain Open
What happened
Sherritt announced on October 20 that the US Treasury’s Office of Foreign Assets Control had issued a specific licence for fuel, fuel oil and sulfur supplies to its Moa Nickel operations in Cuba. The authorisation covers delivery and payment, including related services provided by banks, vessel operators and insurers.
The company expects the first shipment in the fourth quarter. However, a second emergency licence is still required to restart operations. Sherritt also reports constrained liquidity and material uncertainty over its ability to continue as a going concern. Gillon Capital’s proposed acquisition of a controlling interest remains subject to further agreements and approvals.
The investment implication extends across the Cuba to Canada processing chain. Permission to move essential inputs can reopen logistics before production and financing are resolved. Therefore, funding and supply commitments need milestones for the remaining licence, working capital and physical deliveries. The announcement reduces one legal barrier, while the commercial recovery still depends on several conditions being met together.
United States · Offshore mineral rights
US Publishes Final Notice for American Samoa Offshore Mineral Sale
What happened
The Federal Register published the final notice for an offshore mineral sale near American Samoa on October 20. The US Interior Department’s Marine Minerals Administration will auction two areas covering approximately 31.5 million acres on November 19. Each area carries a minimum bonus bid of US$3 million and a primary lease term of 20 years.
The notice covers deposits including polymetallic nodules and ferromanganese crusts. However, the existing environmental assessment covers leasing and preliminary characterisation activities. Extraction requires subsequent plans, approvals and environmental review. Investors therefore need to distinguish the auction timetable from the longer sequence needed to establish a viable operating project.
The strategic significance is the state’s willingness to create access to a prospective mineral frontier. Yet the commercial value of access depends on recoverable resources, viable technology, costs and an acceptable operating framework. This also brings territorial and community interests into the investment decision. The November auction will test demand for these rights; it cannot establish the timing or volume of future mineral supply.
BHP · Copper supply and operating performance
BHP Copper Output Falls 19% While Annual Guidance Holds
What happened
BHP reported September quarter copper production of 400,700 tonnes on October 20, a decline of 19% from a year earlier. Escondida produced 252,600 tonnes, down 23%. Nevertheless, the group retained its financial year 2027 copper guidance of 1.65 million to 1.80 million tonnes.
The company described planned grade changes and maintenance alongside weather disruption in Chile, safety stoppages and the Carrapateena conveyor failure. Separately, it reported a maiden Olympic Dam underground block cave mineral resource of 10,730 million tonnes at 0.59% copper. That resource requires further development work before any potential production can be assessed.
These disclosures operate on different investment horizons. Current supply depends on safe operating performance and recovery from disruption, while the resource supports longer term development options. Accordingly, investors should assess delivery against retained guidance separately from the scale of future resources. A large geological inventory cannot establish near term availability, approved capital expenditure or an operating schedule.
European Union · Arctic resources and infrastructure
EU Arctic Strategy Links Mineral Development to Infrastructure and Safeguards
What happened
The European Commission and High Representative presented a new Arctic strategy on October 20. The framework connects security, economic resilience and sustainable development, including critical raw materials and the transport, energy and digital infrastructure required to support activity in the region.
The communication supports responsible mineral development while reaffirming opposition to deep sea mining until the stated scientific, environmental and regulatory conditions are satisfied. It also places importance on Indigenous rights and environmental protection. Existing funding programmes cited in the strategy should be distinguished from any new project financing decisions.
For investors, the document clarifies a political direction without replacing project approvals or commercial due diligence. Its position on seabed activity also contrasts with the US decision to advance an offshore lease sale. However, the two developments concern different jurisdictions and legal instruments. The practical opportunity remains project specific: connect resources to infrastructure, secure community legitimacy and identify the conditions under which capital can actually be deployed.
The Daily records verified changes. The Signals provide the classification map. The Weekly brings the developments together for the deeper system reading.