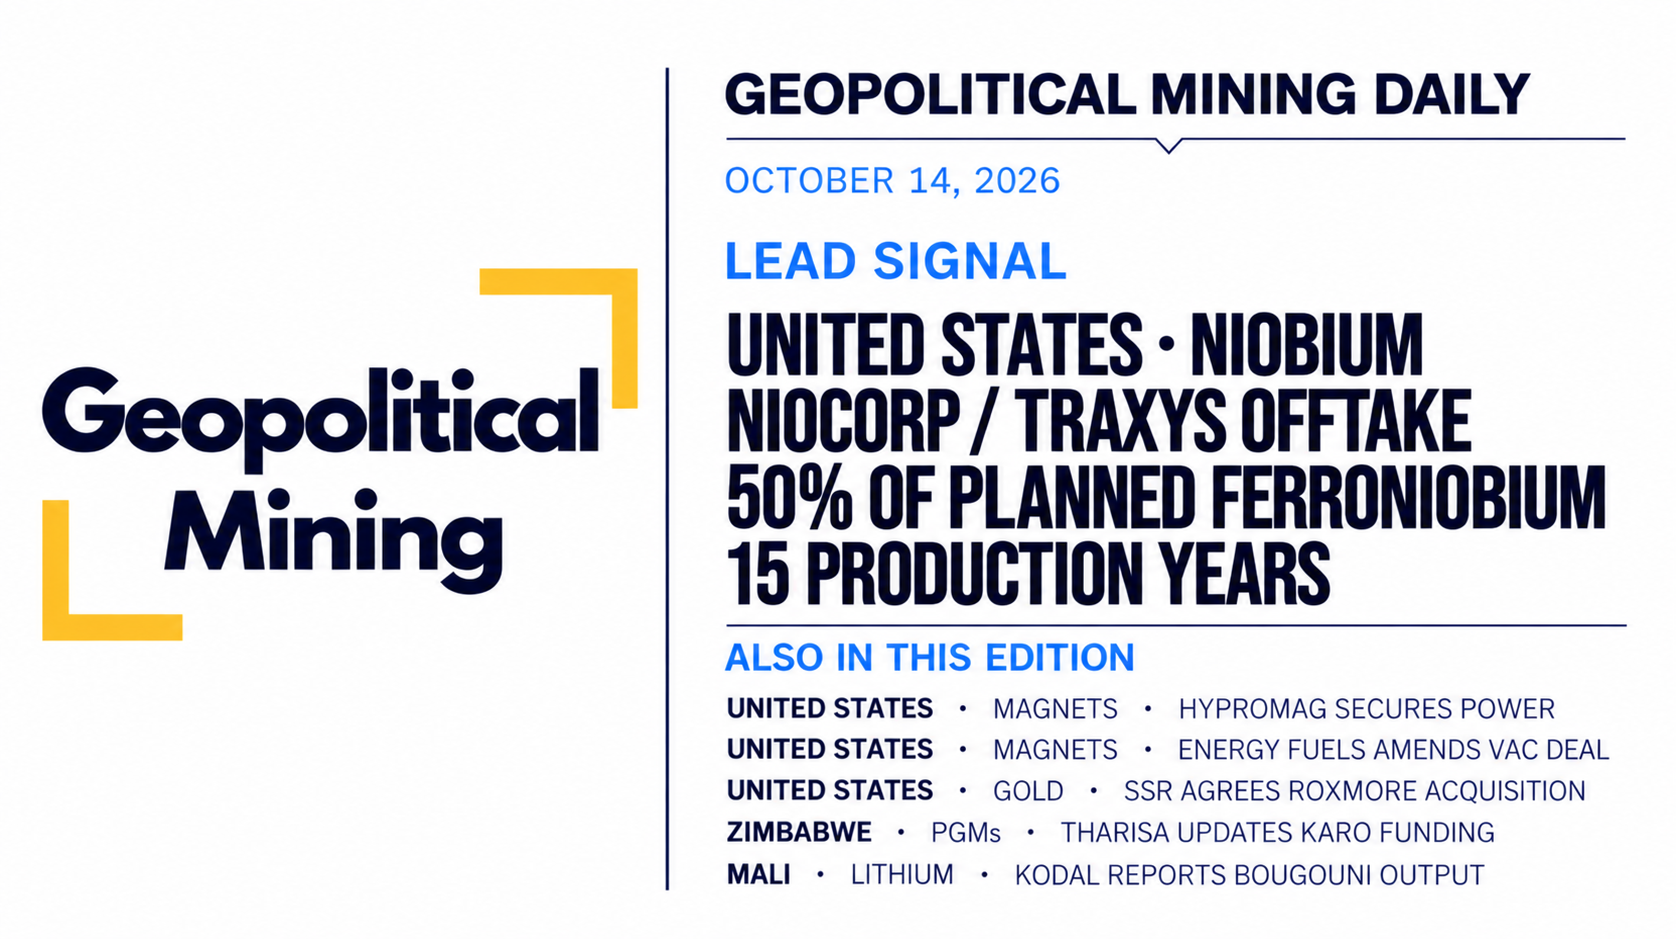
Geopolitical Mining Daily · October 14, 2026
NioCorp Signs Traxys Ferroniobium Offtake for Elk Creek
Geopolitical Mining Daily gives senior executives, investors and policymakers a concise record of verified mining, critical minerals and supply chain developments. This edition begins with the NioCorp Traxys offtake for Elk Creek.
The NioCorp Traxys offtake leads today’s record of mineral sales, magnet manufacturing, acquisition terms and project delivery, alongside operating updates from Zimbabwe and Mali.
The NioCorp Traxys offtake anchors an edition tracking how mineral projects move toward customers and production. It covers Elk Creek’s binding ferroniobium sales agreement, power secured for a Texas magnet hub, amended terms for the planned VAC acquisition, SSR Mining’s Nevada purchase agreement, Karo’s construction and financing update, and Bougouni’s lithium shipments and mining constraints.
The GM observation framework
The ten Signals
Each Daily uses the same ten strategic lenses. The highlighted dimensions classify the developments in this edition.
Lead development
United States · Niobium · NioCorp Signs Traxys Offtake for Elk Creek
What happened
According to NioCorp’s October 13 announcement, its binding Traxys agreement covers 50% of Elk Creek’s planned ferroniobium output for its first 15 production years. Traxys also confirmed the purchase commitment. Meanwhile, the existing ThyssenKrupp agreement covers the other 50% for ten production years and remains unchanged.
The NioCorp Traxys offtake also establishes exclusive marketing and purchase rights for other planned products, including scandium, titanium and rare earths. However, Traxys has no obligation to buy those products. Their sales arrangements therefore differ from the binding ferroniobium commitment.
Before deliveries begin, financing, construction, commercial production and customary ancillary terms must be in place. The agreement advances the project’s commercial arrangements while financing remains pending. However, a possible Traxys equity investment remains separate and uncommitted; the announcement does not establish EXIM financing approval.
Magnet manufacturing readiness
United States · Rare Earth Magnets · HyProMag Secures Power for Texas Hub
What happened
According to HyProMag USA’s October 13 report, Oncor power capacity is secured for initial magnet finishing and Phase 1 in Texas. Pegasus has begun contractor selection, while Weston advances permitting. A later Phase 2 would require a substation upgrade.
Initially, the hub would finish and qualify magnet blocks from other HyProMag operations, with commissioning targeted for the first half of 2027. Integrated recycling and magnet production would then follow in Phase 1, targeted for the middle of 2028.
Phase 1 plans include 550 tonnes a year of magnet blocks and finished magnets, together with 484 tonnes of other saleable products. Accordingly, the stated 1,034 tonnes of total payable output is not all magnets. The update establishes a utility milestone but discloses no new financing amount.
Acquisition terms and customer risk
United States / Germany · Magnets · Energy Fuels Amends VAC Acquisition Terms
What happened
Energy Fuels signed an amendment on October 13 to its pending acquisition of VAC, according to its SEC filing. Specifically, the changes address an e-VAC customer supply contract dispute, a possible settlement, debt repayment and purchase price adjustments.
The filing says the buyer knew about the dispute during negotiations. The purchase price therefore assumes a reasonable settlement, with an adjustment for any shortfall. Consequently, the amendment allocates commercial risk before closing; it does not announce that the customer dispute has been resolved.
The filing also distinguishes current magnet capacity from expansion potential. For example, Sumter, South Carolina, has 2,000 tonnes a year of capacity. However, expansion to 12,000 tonnes would require additional capital and customer offtake agreements. Different customer specifications could also require material capital spending.
Gold portfolio acquisition
United States · Gold · SSR Mining Agrees to Acquire Roxmore
What happened
According to its SEC filing, SSR Mining signed an agreement on October 13 to acquire Roxmore Resources. Converse lies six kilometres west of SSR’s Marigold mine. The offer provides C$6.75 in cash per Roxmore share, together with shares in a separate company retaining exploration assets.
Specifically, SSR values the acquisition at US$464 million in equity, excluding the separate company, and US$392 million in enterprise value. It plans to fund the cash payment from its balance sheet. The transaction would therefore place a nearby development project alongside existing mining infrastructure.
However, Converse production remains a future objective. Under that later development scenario, SSR targets initial output in 2033 and estimates construction capital of US$800 million to US$900 million. Development still requires federal permits, with an environmental impact statement expected. Meanwhile, the acquisition itself remains subject to shareholder and court approvals.
Construction and access to financing
Zimbabwe · Platinum Group Metals · Tharisa Updates Karo Construction and Funding
What happened
According to Tharisa’s October 13 report, investment in Karo has reached US$240 million against a US$516 million capital budget. Meanwhile, construction has moved into fabrication and steel erection. The company still targets first ore to the mill in the fourth quarter of 2027.
However, proceeds from the US$300 million bond issued in September remain in escrow, pending conditions for release. Tharisa expects project drawdowns from November, once it meets those conditions. A further US$75 million local working capital facility is still being finalised.
In contrast, the company’s new financial year 2027 operating guidance covers the existing Tharisa mine in South Africa, excluding Karo. Specifically, it forecasts 150,000 to 170,000 ounces of platinum group metals and 1.50 million to 1.65 million tonnes of chrome concentrate. The report therefore separates operating guidance from the future Zimbabwean capacity.
Lithium shipments and operating constraints
Mali · Lithium · Kodal Reports Bougouni Output and Shipment Revenue
What happened
According to Kodal’s October 13 report, Bougouni produced 27,234 dry tonnes of spodumene concentrate during the third quarter, at 5.29% lithium oxide. The project operator also received US$47 million for its fourth shipment of approximately 24,200 tonnes. The weighted reference price was US$2,330 per tonne on a 6% lithium oxide basis.
Despite mining constraints, the company maintained annual output guidance of 105,000 to 115,000 tonnes. However, equipment availability and wet season delays held mining below budget. Additional equipment and another mining contractor aim to improve the continuity of ore supply.
Meanwhile, work on the proposed flotation expansion continues through metallurgy, environmental studies and feasibility engineering. However, the shipment revenue belongs to the project operator; Kodal’s ultimate economic interest in the project is approximately 32%. No final investment decision on the expansion was announced.
The Daily records verified changes. The Signals provide the classification map. The Weekly brings the developments together for the deeper system reading.