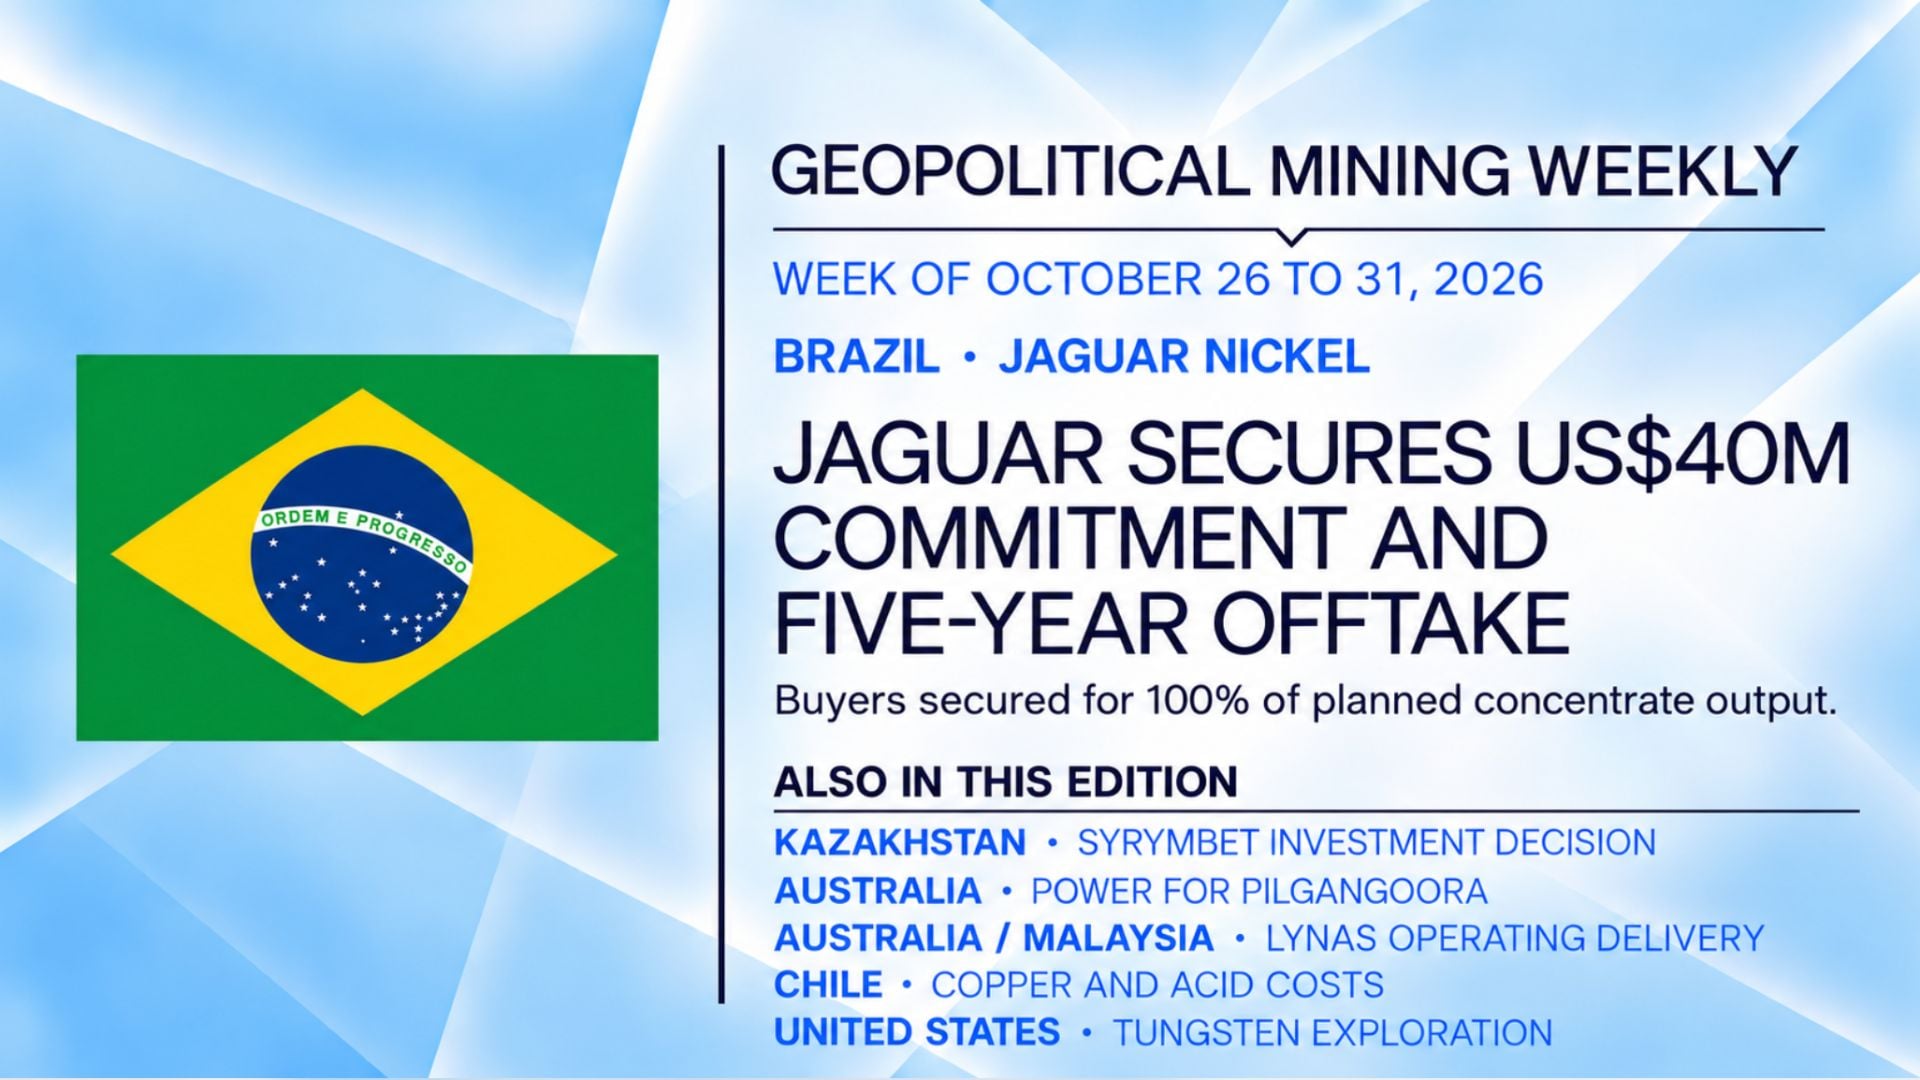
Jaguar Secures US$40M Commitment and Five Year Offtake
The Jaguar nickel project in Brazil secured a US$40 million conditional equity commitment and buyers for its first five years of forecast concentrate output. Elsewhere, a tin investment decision in Kazakhstan, a long power contract in Australia and operating reports from Australia, Malaysia and Chile showed the other work involved in delivering mineral supply. In the United States, staged tungsten support advanced technical work. In practice, buyers, electricity, reagents, technical knowledge and reliable operations all have to come together.
At Geopolitical Mining, we read these developments as parts of the same material economy. For example, a stronger market position can support a project, while a missing input can constrain a producing mine. The comparison helps distinguish progress toward future capacity from the conditions needed to keep today’s supply moving.
A weekly analysis for senior executives, investors and policymakers, connecting mining developments with investment, industrial strategy and public policy.
Evidence base: Daily editions published October 27 to 31 and the official announcements linked below. Coverage: October 26–31, 2026. Editorial cutoff: October 31, 10:20 p.m. EDT.
Cover story · Brazil
Centaurus Metals announced binding offtake agreements on October 28. New Glencore and CNGR contracts, together with an existing agreement, cover forecast concentrate output for Jaguar’s first five years in Brazil.
As a result, the commercial route is clearer. However, senior debt and the final investment decision remain outstanding. Bringing customers into the project advances one part of the work required before construction.
From customer commitment to delivery
Binding contracts establish a route to market.
US$40 million agreed, subject to tranche conditions.
Senior debt remains to be finalised.
First shipments targeted for the first half of 2029.
The strategic question
How does commercial support become a mine that can deliver on its commitments?
What the Jaguar nickel project still needs
The transaction structure links customers, equity and future deliveries. Yet each commitment has its own conditions. In particular, the second equity tranche depends on shareholder approval and a final investment decision; CNGR also requires outbound investment approval. Buyers can terminate if first shipment has not occurred by the end of 2029.
Consequently, those terms explain why a commercial announcement deserves close reading. In particular, they give the developer a stronger basis for advancing the project, while keeping financing and execution visible. Across this week’s other developments, the same practical question appears in different forms: what has become possible, and what work remains before industry receives the material?
Commitments, inputs and operating results
US$40 million
Jaguar strategic equity
Brazil · Conditional commitments, rather than cash fully received.
325 GWh
Minimum annual electricity
Australia · Physical connection and backup generation remain necessary.
A$150 million
PLS connection investment
Australia · Planned transmission and related infrastructure across FY27–29.
2,082 tonnes
Lynas ready-for-sale NdPr
Australia / Malaysia · Record output for the September quarter.
Six readings from the week
Customers can support a mine before financing is complete. At Jaguar in Brazil, customer commitments improve the project’s commercial position, while financing conditions and delivery dates remain material.
An investment decision starts a different phase of work. Syrymbet in Kazakhstan advances toward construction, while funding and execution still separate approval from output.
Power supply is part of the mine’s production system. For PLS in Australia, a long electricity contract supports planning, while connection infrastructure determines how power reaches the operation.
Existing operations determine how much supply reaches industry. Lynas’s chain across Australia and Malaysia demonstrates the importance of operating the whole system, while other producers face different immediate constraints.
A reagent can change the production plan. At Capstone’s operations in Chile, acid costs show how an essential input can affect the amount of copper that is economic to produce.
Technical work creates the basis for future industrial options. In the United States, staged tungsten support funds feasibility work, while further evidence and approvals determine the next steps.
Customers can support a mine before financing is complete
The Jaguar agreements connect customer demand with a prospective Brazilian nickel mine. However, the financing process is still open. In addition, a buyer’s equity participation brings a different form of involvement from a purchase contract, even when the same company signs both.
For a developer, this can improve the basis for discussions with lenders. For example, a clearer sales route reduces one source of uncertainty, while agreed equity provides a potential contribution to the funding plan. Nevertheless, neither arrangement removes construction risk or establishes the cash needed for every stage.
However, the relationship also creates obligations. Because customers plan their own operations around future deliveries, project timing becomes part of the commercial arrangement. Delays can therefore affect more than the capital budget. They can change the terms on which the planned output remains committed.
This is where mineral security meets the core business of mining. In other words, a resource must support a product that customers can use, at a price and on a schedule that sustain the operation. As a result, commercial progress has to be assessed together with engineering and financing readiness.
An investment decision starts a different phase of work
Solidcore Resources approved Syrymbet’s final investment decision on October 29. The Kazakhstan tin and copper project has initial capital of US$468 million. Bank loans and shareholder contributions form the planned funding mix, while first production is targeted for the second half of 2029.
Its quarterly update places the decision within Solidcore’s wider development programme. Meanwhile, environmental work for international lenders continues. The board has authorised the investment, but the announcement does not establish that the entire financing package has closed.
Next, the project faces a sequence of practical commitments: completing financing, placing contracts, building facilities and bringing the plant into operation. Moreover, these steps carry different risks and draw on different skills. Consequently, an approved capital figure should be read alongside the arrangements for spending it.
The new EIB framework with Canada illustrates an earlier institutional stage. It opens a route for eligible investment proposals to be considered. However, project approvals and actual financing remain separate decisions. Comparing the two developments shows why access to capital, approval to invest and delivery of capacity deserve distinct treatment.
Power supply is part of the mine’s production system
PLS Group Limited signed a 20-year power agreement on October 28 for Pilgangoora in Western Australia. It targets supply from 2029, with a minimum of 325 GWh annually. However, the supply is not firm. PLS plans A$150 million in connection infrastructure. It also needs additional on-site generation, while contractual conditions remain.
A power purchase agreement links an operating site to an electricity supplier over a long period. However, the mine still needs a dependable physical connection and a workable response to interruptions. Therefore, those requirements place infrastructure and backup arrangements inside the operating plan.
This matters because processing capacity is only useful when the plant can run. In particular, energy availability, reliability and cost influence throughput and margins together. As a result, a favourable supply contract can leave substantial engineering and capital work with the mining company.
More broadly, the lesson concerns how industrial projects are assessed. Electricity should be treated as part of the production system from the outset, alongside mining and metallurgy. Otherwise, an investment can add nominal plant capacity while leaving the conditions for using it unresolved.
Existing operations determine how much supply reaches industry
Lynas Rare Earths reported record quarterly ready-for-sale NdPr production of 2,082 tonnes. Price floors cover more than half of production. However, planned maintenance in Malaysia and a power interruption at Kalgoorlie in Western Australia are expected to reduce December-quarter output.
In practice, an integrated mineral chain must coordinate mining, processing, maintenance and customer deliveries. Strong production at one stage is valuable, but performance elsewhere can still affect the volume available for sale. Consequently, the location of a resource tells only part of the supply story.
This week also brought a progressive underground restart at Oyu Tolgoi in Mongolia after safety reviews. Meanwhile, Cameco narrowed its Canadian uranium production guidance, reducing the upper end while retaining the lower end. However, these are different operating events, rather than a single common disruption.
Together, they keep attention on the work required to sustain current supply. Maintenance, technical performance and safe operating conditions can change delivery well before a new project reaches production. Therefore, industrial strategies need a view of existing assets as well as the development pipeline.
A reagent can change the production plan
Capstone Copper reported sulphuric acid costs of US$316 per tonne at Mantos Blancos in Chile, up from US$186 a year earlier. Meanwhile, its oxide plan at Mantoverde, also in Chile, reduces cathode output by approximately 5,000–8,000 tonnes to limit exposure to costly spot acid. The adjustment concerns oxide production, while sulphide operations follow a different process.
Sulphuric acid is part of the route from certain copper ores to saleable metal. When its cost rises, the response can extend beyond a higher operating expense. Material that was economic under one input assumption may become less attractive to process.
The effect therefore runs through production planning, working capital and margins. Access to ore and installed equipment does not settle the decision to use them at every available rate. Therefore, operating choices must reflect the cost and reliability of the inputs that make recovery possible.
In other words, this is a practical form of exposure to the wider industrial system. For example, mines depend on chemical producers, transport and commercial terms outside their own boundaries. As a result, input procurement deserves a place in mineral supply analysis alongside reserves, project approvals and funding announcements.
Technical work creates the basis for future industrial options
Perpetua Resources announced US Army support on October 26 to assess tungsten at Stibnite in Idaho, United States. The committed 18-month phase totals US$18 million, split equally with the company. However, further phases require approval.
Consequently, the work builds a technical basis for a possible tungsten operation. Further development requires its own permissions.
The DOE workforce prize launched on October 30 addresses another part of industrial capability. Its potential funding supports training through universities in the United States. Although skilled people and technical evidence serve different purposes, both help determine whether future capacity can be developed and operated.
Therefore, strategic interest can bring resources to this work earlier. Its industrial value emerges as knowledge becomes a credible process, qualified people and an executable project. Therefore, feasibility programmes and workforce initiatives should be assessed against the capabilities they are intended to build.
Supply depends on the ability to produce
In summary, the week brings mineral security back to the business of mining. Customers and funding can advance a development, while power, reagents and operating knowledge determine how the production system works. Moreover, these conditions interact. A stronger sales position helps a project move forward, but its eventual performance still depends on the facilities and people that deliver the product.
For investors, that means following the use of capital as closely as its availability. For policymakers, it means considering the industrial services and skills that sit around a mine. Meanwhile, operators must keep testing production plans against the actual cost and reliability of essential inputs.
Finally, the next evidence will come through financing conditions, construction contracts, technical results and operating reports. Together, those steps will show whether this week’s commercial and investment progress translates into capacity that can run reliably and earn a return.
Dates and decisions to watch
December quarter 2026
Planned maintenance and power interruption affect the output outlook.
January 31, 2027
Second-tranche sunset date under the announced agreements.
Initial 18 months
Technical feasibility work; further phases require approval.
2029 target
Connection work and contractual conditions precede delivery.
Second half of 2029
First output target, followed by full ramp-up in 2030.
The Daily archive behind this reading
These editions preserve the individual developments and their sources. The Weekly compares their implications across the mineral system.
US Army Backs Perpetua Tungsten Exploration
28 October, 2026Nova Antimony Project Receives Final Alaska Permits
29 October, 2026Jaguar Nickel Project Secures Offtake Agreements
30 October, 2026Syrymbet Tin Project Reaches Investment Decision
31 October, 2026EIB Opens Financing Route for Canadian Critical Minerals
Primary documents behind the Weekly
Company and institutional announcements establish the reported facts. The comparisons and implications above are Geopolitical Mining’s analysis.
Centaurus Metals
Jaguar strategic offtake and conditional equity, October 28
MPH Lawyers
Adviser account of Jaguar commercial and financing agreements, October 28
Solidcore Resources
Syrymbet investment decision, October 29
Solidcore Resources
Third quarter production results, October 30
Perpetua Resources
Staged US Army tungsten feasibility award, October 26
European Investment Bank
Financing framework with Canada, October 30
Rio Tinto
Oyu Tolgoi seismic event and progressive restart, October 30
Cameco
Third quarter results and production guidance, October 30
US Department of Energy
PROSPECT Implementation Prize, October 30
PLS Group Limited
Long-term power agreement, October 28
Lynas Rare Earths
September quarterly report, October 29; issuer report mirror
Capstone Copper
Third-quarter results, October 29
GM Signals provides the observation framework. The Daily records developments and their stage. The Weekly then compares the evidence. It identifies what changed across the mineral system.