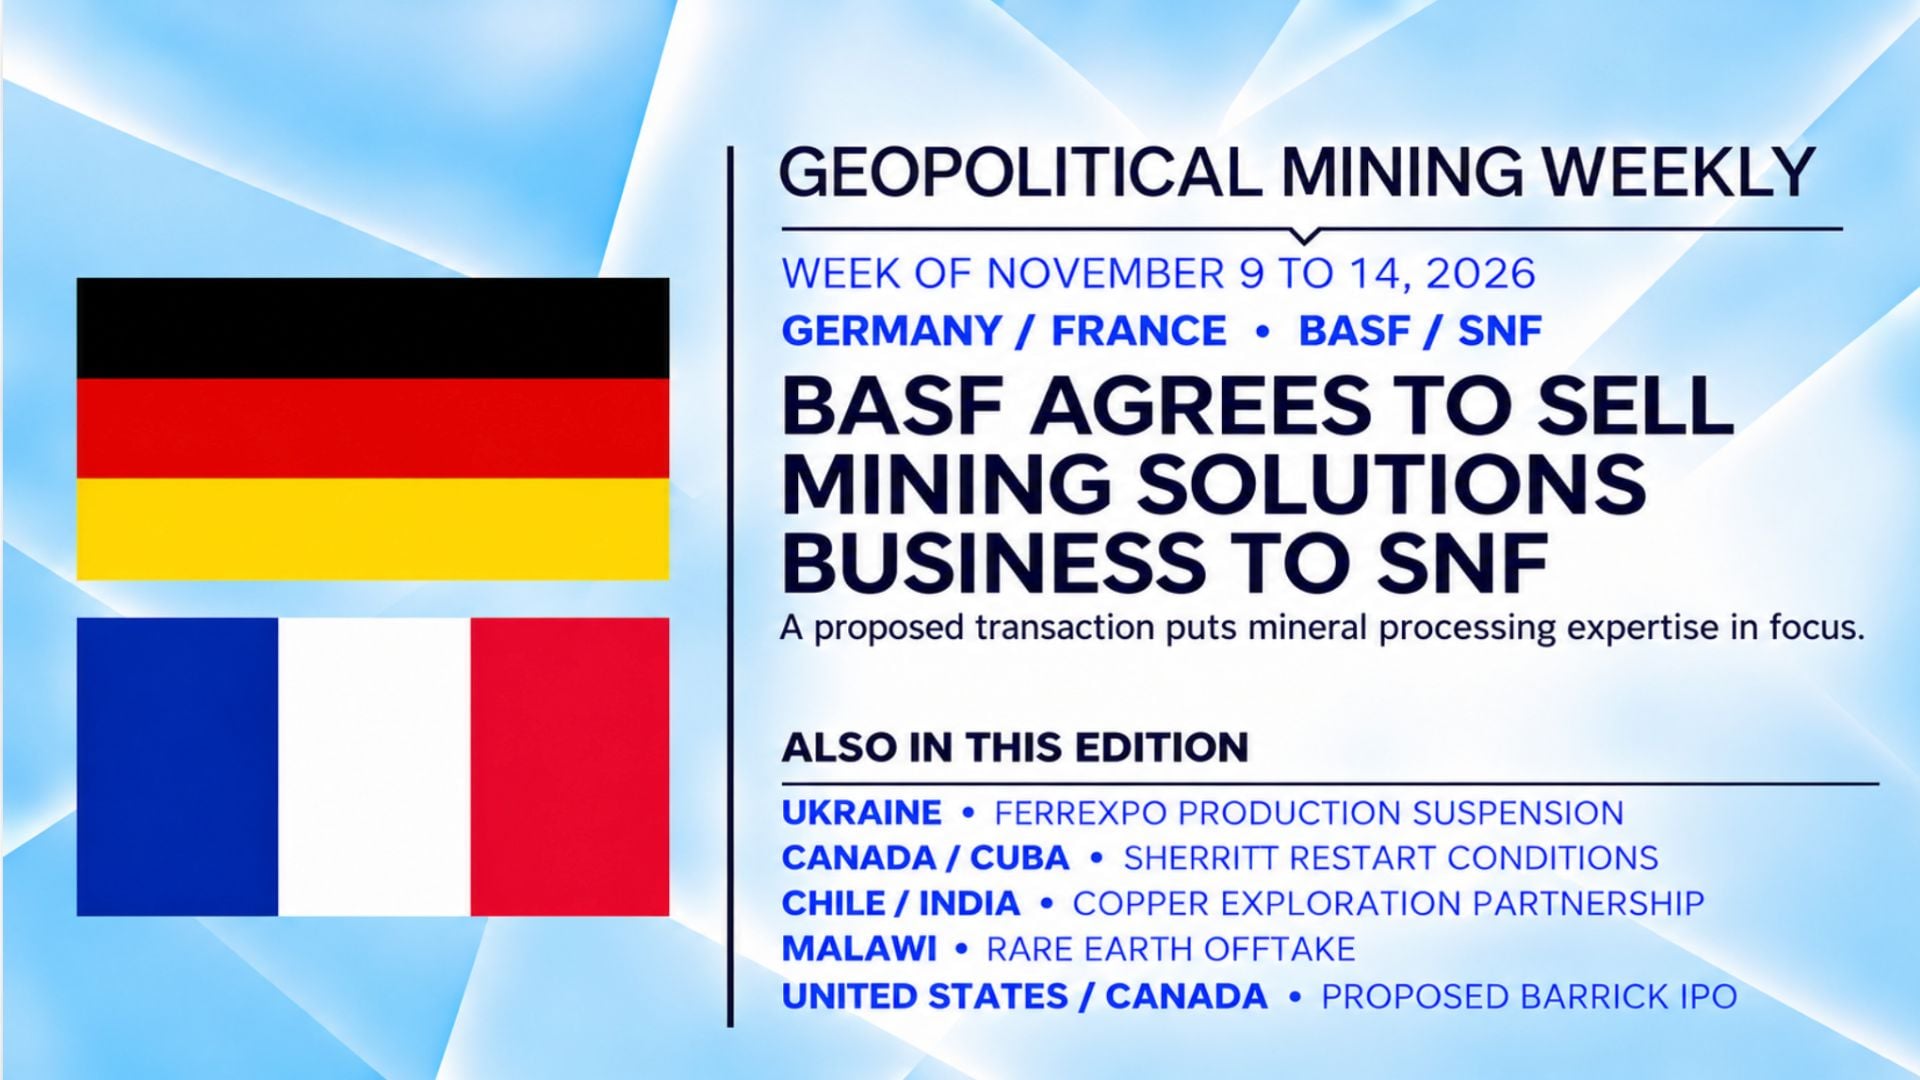
Germany and France: BASF’s Mining Solutions Sale Puts Industrial Know-How in Focus
Mineral supply depends on more than access to deposits. BASF’s agreement to sell its mining solutions business to SNF brings another part of the industry into view: the chemicals, manufacturing facilities and technical knowledge used to recover metals from ore.
The proposed transfer includes a production site in Ireland and approximately 140 employees. Alongside this transaction, the week’s developments show how electricity, regulatory permissions, exploration partnerships, commercial agreements and capital markets shape the conditions in which mineral assets can operate and reach industry.
A weekly analysis for senior executives, investors and policymakers, connecting mining developments with investment, industrial strategy and public policy.
Evidence base: selected developments reported during November 9 to 14, 2026, the Daily archive and original sources linked below. Published November 15, 2026.
Cover story · Germany / France / Ireland
BASF’s November 12 agreement with SNF covers its mining solutions business, including the Cork production site and approximately 140 employees.
The sale brings attention to the specialist chemicals and technical expertise that connect mineral deposits with industrial production.
The industrial capability behind processing
Reagents used in flotation, leaching and solvent extraction.
Specialist teams and a manufacturing base in Ireland.
Closing expected in 2027, subject to approvals and other conditions.
The strategic question
What industrial knowledge and capabilities are needed to turn a mineral resource into a saleable product?
Operating constraints and commercial commitments
Six readings from the week
- Germany / France / Ireland: Industrial Capabilities Extend Beyond Deposits.
- Ukraine: Electricity Infrastructure Is Part of Mineral Supply.
- Canada / Cuba: Regulatory Access Connects Operations Across Borders.
- Chile / India: Exploration Partnerships Connect Industrial Needs.
- Malawi: Commercial Commitments Help Organise Future Supply.
- United States / Canada: Corporate Structure Changes Access to Mining Assets.
Germany / France / Ireland: Industrial Capabilities Extend Beyond Deposits
BASF agreed to sell its mining solutions business to France’s SNF. The transaction includes the Cork production site in Ireland and approximately 140 employees. The business supplies reagents used in flotation, leaching and solvent extraction. Closing is expected in 2027, subject to merger approvals and customary conditions; the purchase price was not disclosed. BASF and SNF announcement
These activities sit between a mineral resource and a saleable product. Reagents and the expertise required to apply them are part of the industrial capability that allows mines to recover and process material. Their importance is less visible than that of a deposit or a smelter, but they belong to the same production system.
The agreement changes the proposed ownership of that capability. It does not yet establish a change in customers’ costs, recovery rates or access to products. For now, the development is the planned transfer of a specialist business, its manufacturing base and its people to another supplier serving the mining industry.
Ukraine: Electricity Infrastructure Is Part of Mineral Supply
Ferrexpo announced a temporary suspension of production on November 10 following further attacks on Ukraine’s electricity transmission network and substations. Supply had become too unstable and insufficient to sustain operations. The company said its assets were undamaged and that European customers continued to receive material from inventory. Ferrexpo announcement
The distinction matters. Mining capacity is not confined to the equipment and infrastructure inside a company’s boundary. It also depends on the networks that deliver electricity to extraction, processing and transport operations. In this case, damage outside Ferrexpo’s sites was enough to interrupt production inside them.
Inventory provides a bridge between production and deliveries, but it does not resolve the underlying electricity constraint. Ferrexpo said it would resume operations when commercially viable conditions allowed. That leaves the restart dependent on both the availability of power and the conditions under which it can be supplied. The company gave no restart date.
Canada / Cuba: Regulatory Access Connects Operations Across Borders
Sherritt’s November 13 results showed no finished nickel or cobalt production in the third quarter. The company suspended direct participation in its Cuban joint venture in May following a U.S. executive order. Fuel and other input disruptions subsequently stopped mining and processing in Cuba, while its Canadian refinery exhausted available feed in June. Sherritt announcement
An October 19 OFAC licence authorised fuel, fuel oil, sulphur and related services. Sherritt described it as the first in a series of anticipated licences needed to support a restart, with no assurance that further authorisations would be granted. The results therefore describe a possible route back to production, not a completed restart.
The operations also show how regulatory exposure travels through a production chain. Refining in Canada does not remove dependence on the jurisdiction supplying its intermediate material. Access to inputs, permissions and feedstock must work together before the combined system can operate. A licence can remove one obstacle without resolving the others.
Chile / India: Exploration Partnerships Connect Industrial Needs
Codelco and Kutch Copper, part of the Adani Group, signed an MOU setting out key commercial terms for a prospective exploration partnership at Kaburkaala, near Calama in Chile. Announced on November 11, it follows technical due diligence under an earlier agreement signed in 2025. Codelco announcement
The proposed partnership brings together different capabilities and interests. Codelco contributes geological knowledge, while Adani brings capital and execution capacity. Codelco also placed the initiative within the relationship between Chile’s copper resources and India’s expanding industrial demand, including Kutch Copper’s smelter at Mundra.
Exploration is the stage at which that relationship begins to take a physical shape, through the allocation of work, capital and geological risk. It remains far from a producing mine. The MOU does not establish a new copper supply stream or guarantee deliveries to India. Its significance lies in the effort to build an upstream position around a longer term industrial relationship, with further agreements and exploration results still to come.
Malawi: Commercial Commitments Help Organise Future Supply
Lindian announced a binding term sheet with a major rare earth refinery for monazite concentrate from Kangankunde. The November 10 announcement set out an initial 10,000 dry metric tonnes over one year from January 2027, followed by a proposed second stage of 20,000 tonnes annually for five years. The buyer was not named. Lindian announcement
The stages should not be treated as current production. Deliveries remain subject to full offtake and delivery contracts, production and relevant approvals. The second stage also depends on regulatory quotas and operational conditions. Lindian planned the first shipment through Nacala for January 2027.
Offtake arrangements connect mine development with the processing system that will receive its output. They establish a commercial basis around specifications, volumes and delivery, helping to define how a project can enter an existing industrial chain. Here, however, the product is concentrate, not separated rare earth oxides or finished magnets. The agreement concerns one link in that chain, and the planned supply has yet to become physical deliveries.
United States / Canada: Corporate Structure Changes Access to Mining Assets
Barrick announced the filing of a registration statement for a proposed initial public offering of American Barrick Gold Corp., a vehicle for its North American gold assets. The company intends to seek a New York Stock Exchange listing under the symbol ABGC. The registration statement was not yet effective, and the number of shares and offering price had not been determined. Barrick announcement
A separate listing would give investors a distinct portfolio to assess, rather than exposure only through the wider Barrick group. That changes the structure through which capital markets value and hold the assets. It does not, by itself, add mining capacity or establish a new production plan.
Barrick said the expected net proceeds would go to the parent company and were intended to be returned to shareholders. The proposed transaction should therefore be distinguished from financing committed directly to new mines. Its immediate importance is corporate and financial: a different ownership structure and a more specific investment vehicle, subject to regulatory and market conditions.
Mineral Supply Also Depends on Industrial Knowledge
BASF and SNF bring the industrial knowledge behind mineral processing into focus. The planned sale concerns specialist products, people and manufacturing capability, rather than ownership of a deposit. Ferrexpo and Sherritt, in turn, show how electricity and regulatory access can determine whether installed facilities operate. Meanwhile, the Codelco and Lindian announcements show companies building the relationships through which future resources may reach markets.
Barrick introduces a different dimension: how those assets are organised for investors. That distinction matters. A commercial agreement, a regulatory permission and a capital transaction each changes something, but they do not all add supply in the same way.
For Geopolitical Mining, the common question is how resources, infrastructure, institutions and industrial capabilities work together. Mineral availability cannot be assessed from geology alone. It also depends on whether the organisations and relationships around the resource can sustain production and connect it with demand.
Dates and decisions to watch
The Daily archive behind this reading
The Daily records individual developments. This Weekly connects selected evidence with the original announcements.
Sources behind the Weekly
Original company announcements establish the reported facts. The comparisons and implications above are Geopolitical Mining’s analysis.
BASF and SNF
Mining solutions sale agreement, November 12
Ferrexpo
Temporary production suspension, November 10
Sherritt
Third quarter results, November 13
Codelco
Kaburkaala exploration memorandum, November 11
Lindian
Kangankunde offtake term sheet, November 10
Barrick
American Barrick proposed IPO, November 10
GM Signals provides the observation framework. The Daily records developments and their stage. The Weekly then compares the evidence to identify what changed across the mineral system.