Geopolitical Mining Daily · November 4, 2026
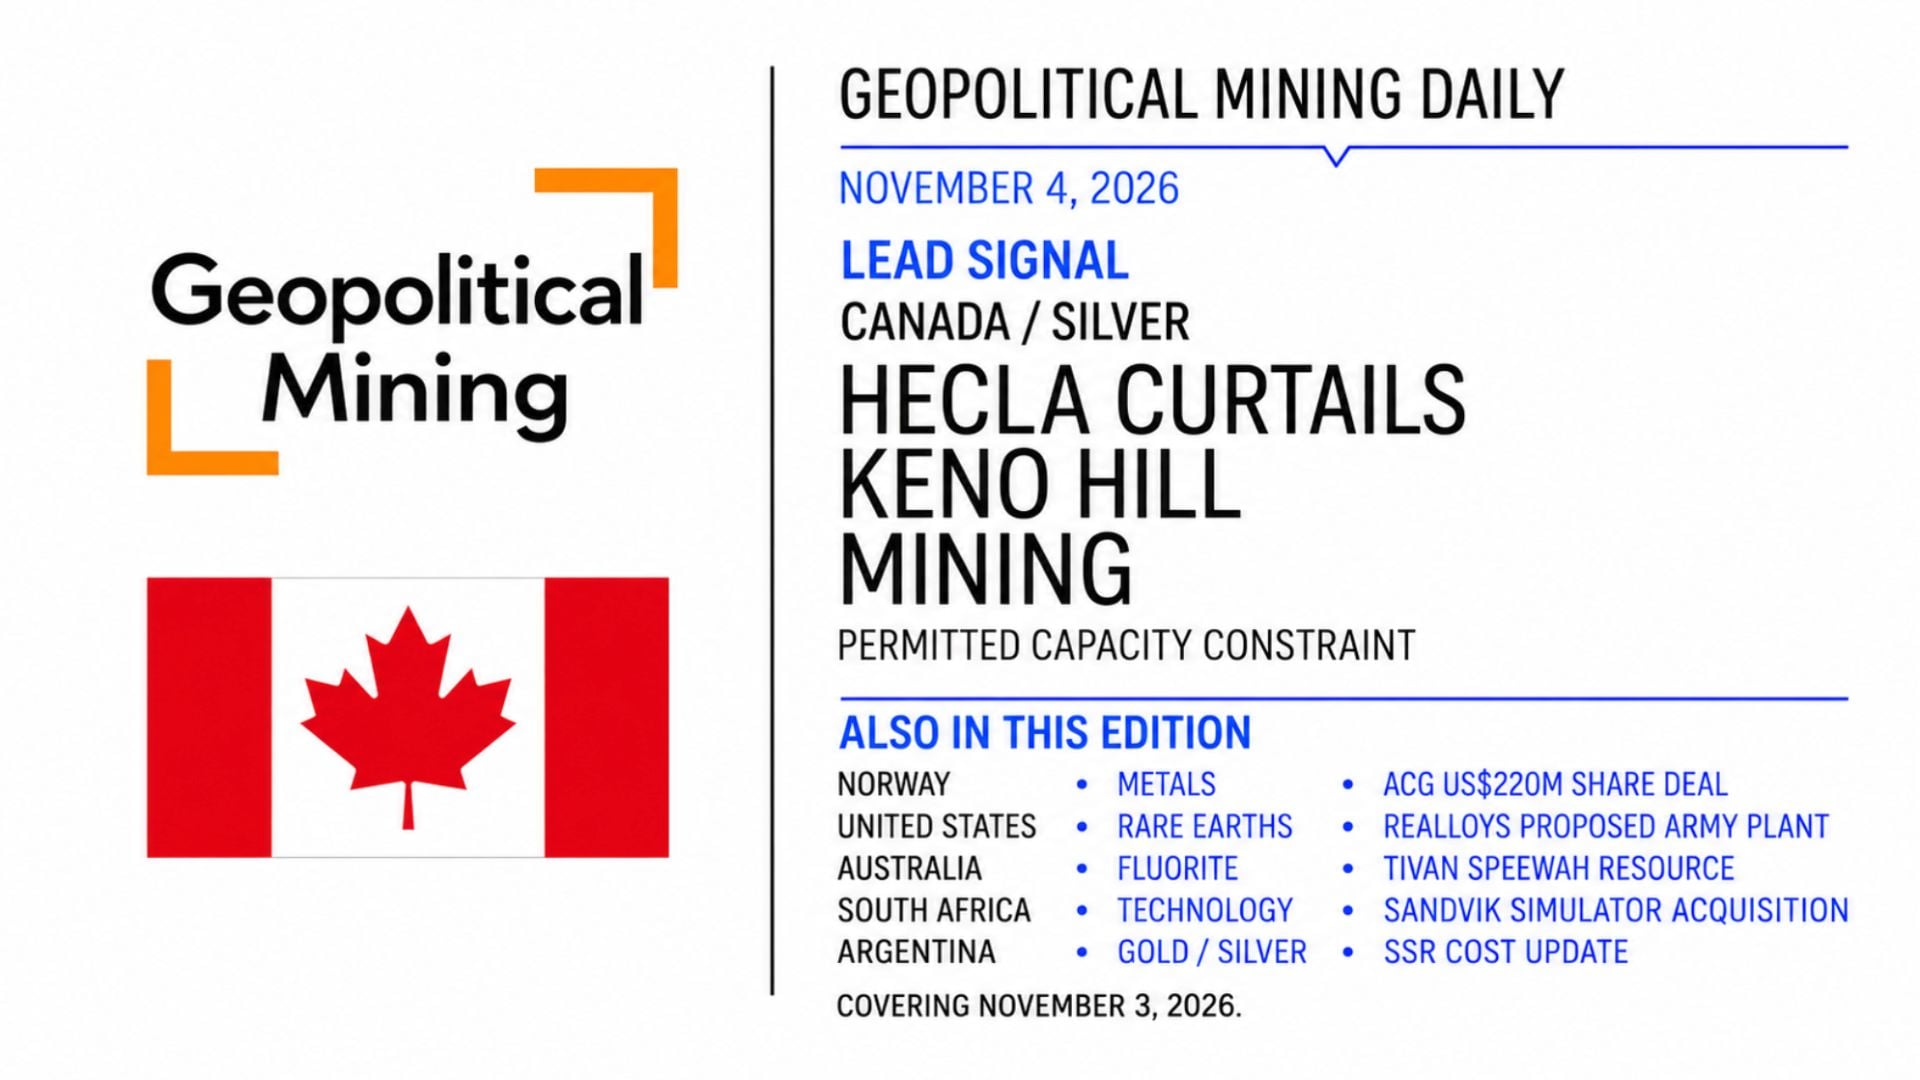
Hecla to Cut Milling at Canada’s Keno Hill Silver Mine
Hecla Mining, the US-based silver producer, plans to reduce milling at Keno Hill in Canada to conserve the tailings, waste rock and water treatment capacity available under its current permits. Further reductions are expected from January 2027.
Elsewhere, copper assets are changing hands, rare earth processing plans are taking shape, and resource studies, training technology and operating costs are influencing mining decisions.
Keno Hill’s operating plan shows how permitted waste and water capacity can limit the use of a mine and mill. The other developments concern different parts of the production chain: ownership of a copper project under construction in Norway, proposed access to US Army land for rare earth processing, the geological basis for an Australian fluorite mine, training services and the cost of extending a silver operation in Argentina.
The GM observation framework
The ten Signals
Each Daily uses the same ten strategic lenses. The highlighted dimensions classify the developments in this edition.
Canada · Silver operating capacity
Canada: Hecla plans lower milling rates at Keno Hill
What happened
Hecla’s November 3 results set out a plan to mill approximately 300 tons per day at Keno Hill, in Yukon, during the fourth quarter. A further reduction is expected from January 2027. The company intends to retain the lower rate until licence amendments are received and the associated infrastructure is built.
Hecla currently estimates receipt of the amendments around mid-2029. It plans to prioritise higher-grade ore and stockpile lower-grade material, so silver output could fall less sharply than throughput. The company expects to issue its 2027 production guidance in February.
The immediate operating constraint is the capacity authorised for tailings, waste rock and water treatment. Higher grades can help preserve metal output while less ore is processed, but they cannot extend those permissions. The mine plan must therefore fit the remaining permitted capacity through an uncertain approval and construction period, making the timing of both central to Keno Hill’s production outlook.
Primary issuer announcement
Hecla Mining · Third-quarter results · November 3, 2026Norway · Copper project ownership
Norway: ACG agrees US$220M share deal for Blue Moon’s assets
What happened
ACG Metals, the London-listed copper producer, agreed to acquire Blue Moon Norway from Canadian project developer Blue Moon Metals for US$220 million in shares, subject to adjustments. The Norwegian subsidiary holds the construction-stage Nussir copper project and the exploration-stage NSG property.
The November 3 agreement would give Blue Moon approximately 8.85 million ACG shares, representing 27.6% of ACG on a basic basis. Closing is targeted for November 30, subject to ACG shareholder approval, TSX Venture Exchange approval and other conditions. Blue Moon plans to repay drawn Nussir project debt at closing and concentrate on its US critical metals assets.
The proposed transaction would put Nussir’s next construction phase under a new owner while leaving Blue Moon exposed to its progress through an equity holding. This changes where development responsibility and financial exposure sit. Completion of the sale, the handover between construction teams and delivery of the remaining project work will determine how smoothly the ownership change translates into an operating mine.
Primary issuer announcement
Blue Moon Metals · Norwegian asset sale · November 3, 2026United States · Heavy rare earth processing
United States: REalloys and the Army outline a potential Utah lease
What happened
US rare earth materials developer REalloys announced a nonbinding term sheet with the US Army for a processing facility at Tooele Army Depot in Utah. The November 3 framework covers about 200 acres and a potential 50-year lease, with a conditional 25-year renewal option.
REalloys would finance, build, operate and eventually decommission the facility, targeting dysprosium and terbium processing. The Army would retain land ownership and have a right of first offer for products, without an obligation to buy them. A definitive lease still requires financing, environmental and permitting work, security review and other approvals.
The arrangement sets out a route for using defence land to support domestic processing. It also leaves the development and commercial tasks with the company: securing capital, completing the plant and finding customers. The lease negotiations will establish the terms of site access; the project’s financing and procurement arrangements will determine whether that access can support an operating supply chain.
Primary issuer announcement
REalloys · Tooele term sheet · November 3, 2026Australia · Fluorite resource definition
Australia: Tivan upgrades confidence in Speewah’s fluorite resource
What happened
Australian developer Tivan reported an updated resource for its Speewah Fluorite Project in Western Australia on November 3. The estimate totals 45.0 million tonnes at 7.8% calcium fluoride, using a 2% cut-off grade. It includes 37.9 million tonnes classified as Indicated, following closer-spaced drilling.
SRK Consulting prepared the estimate to support the project’s detailed feasibility work. Tivan is developing Speewah with Japanese trading group Sumitomo Corporation and state resource agency JOGMEC, targeting acid-grade fluorspar for export. The updated classification provides material that can be considered for an Ore Reserve estimate; the release does not declare a reserve or an investment decision.
The main gain is a firmer geological basis for choosing what to mine and when. A larger Indicated component gives engineers more reliable information for mine design and production scheduling. The feasibility work must still bring that information together with processing performance, infrastructure, costs and approvals. Those results will show how much of the identified mineralisation can support the proposed operation.
Primary issuer announcement
Tivan · ASX resource announcement · November 3, 2026South Africa · Mining training technology
South Africa: Sandvik completes ThoroughTec Simulation acquisition
What happened
Swedish mining equipment group Sandvik completed its acquisition of ThoroughTec Simulation, the South African supplier of equipment simulators and simulator-based training. The November 3 announcement places the business in Parts and Services within Sandvik’s Mining business area.
ThoroughTec is based in Durban, employs more than 200 people and serves the global mining industry through a sales and support network. Its 2025 revenue was approximately SEK 170 million. Sandvik did not disclose a purchase price in the completion announcement.
The acquisition brings operator training closer to an equipment supplier’s service offering. Simulators allow training around machine operation before or alongside work on production equipment, giving skills development a place in the wider operating support business. The completed transaction transfers an established capability and customer network. Its practical contribution at mines will depend on how training is integrated with equipment use, supervision and the operating conditions crews encounter.
Primary issuer announcement
Sandvik · Acquisition completion · November 3, 2026Argentina · Silver mine planning and costs
Argentina: SSR Mining flags cost pressure as Puna’s mine plan changes
What happened
SSR Mining, the Denver-based gold and silver producer, said its Puna operation in Argentina is resequencing production as it identifies additional ore that could extend mine life. Processing of lower-cost stockpiles previously planned for 2026 is being deferred. The update accompanied its November 3 quarterly results.
Puna produced about 1.7 million ounces of silver in the third quarter and reported all-in sustaining costs of US$25.64 per payable ounce. The changed sequence and Argentine inflation are pushing Puna above its annual cost guidance. Separately, SSR expects group-wide all-in sustaining costs to run about 10% above the upper end of its 2026 guidance.
The operating choice trades some lower-cost production today for access to ore that may support a longer mine life. That can alter near-term margins even while the resource outlook improves. Assessing the change requires both schedules: the cost and output of the revised annual plan, and the additional production the longer-term plan can deliver. The potential extension remains dependent on further technical and development work.
Primary issuer announcement
SSR Mining · Third-quarter results · November 3, 2026The Daily records verified changes. The Signals provide the classification map. The Weekly brings the developments together for the deeper system reading.