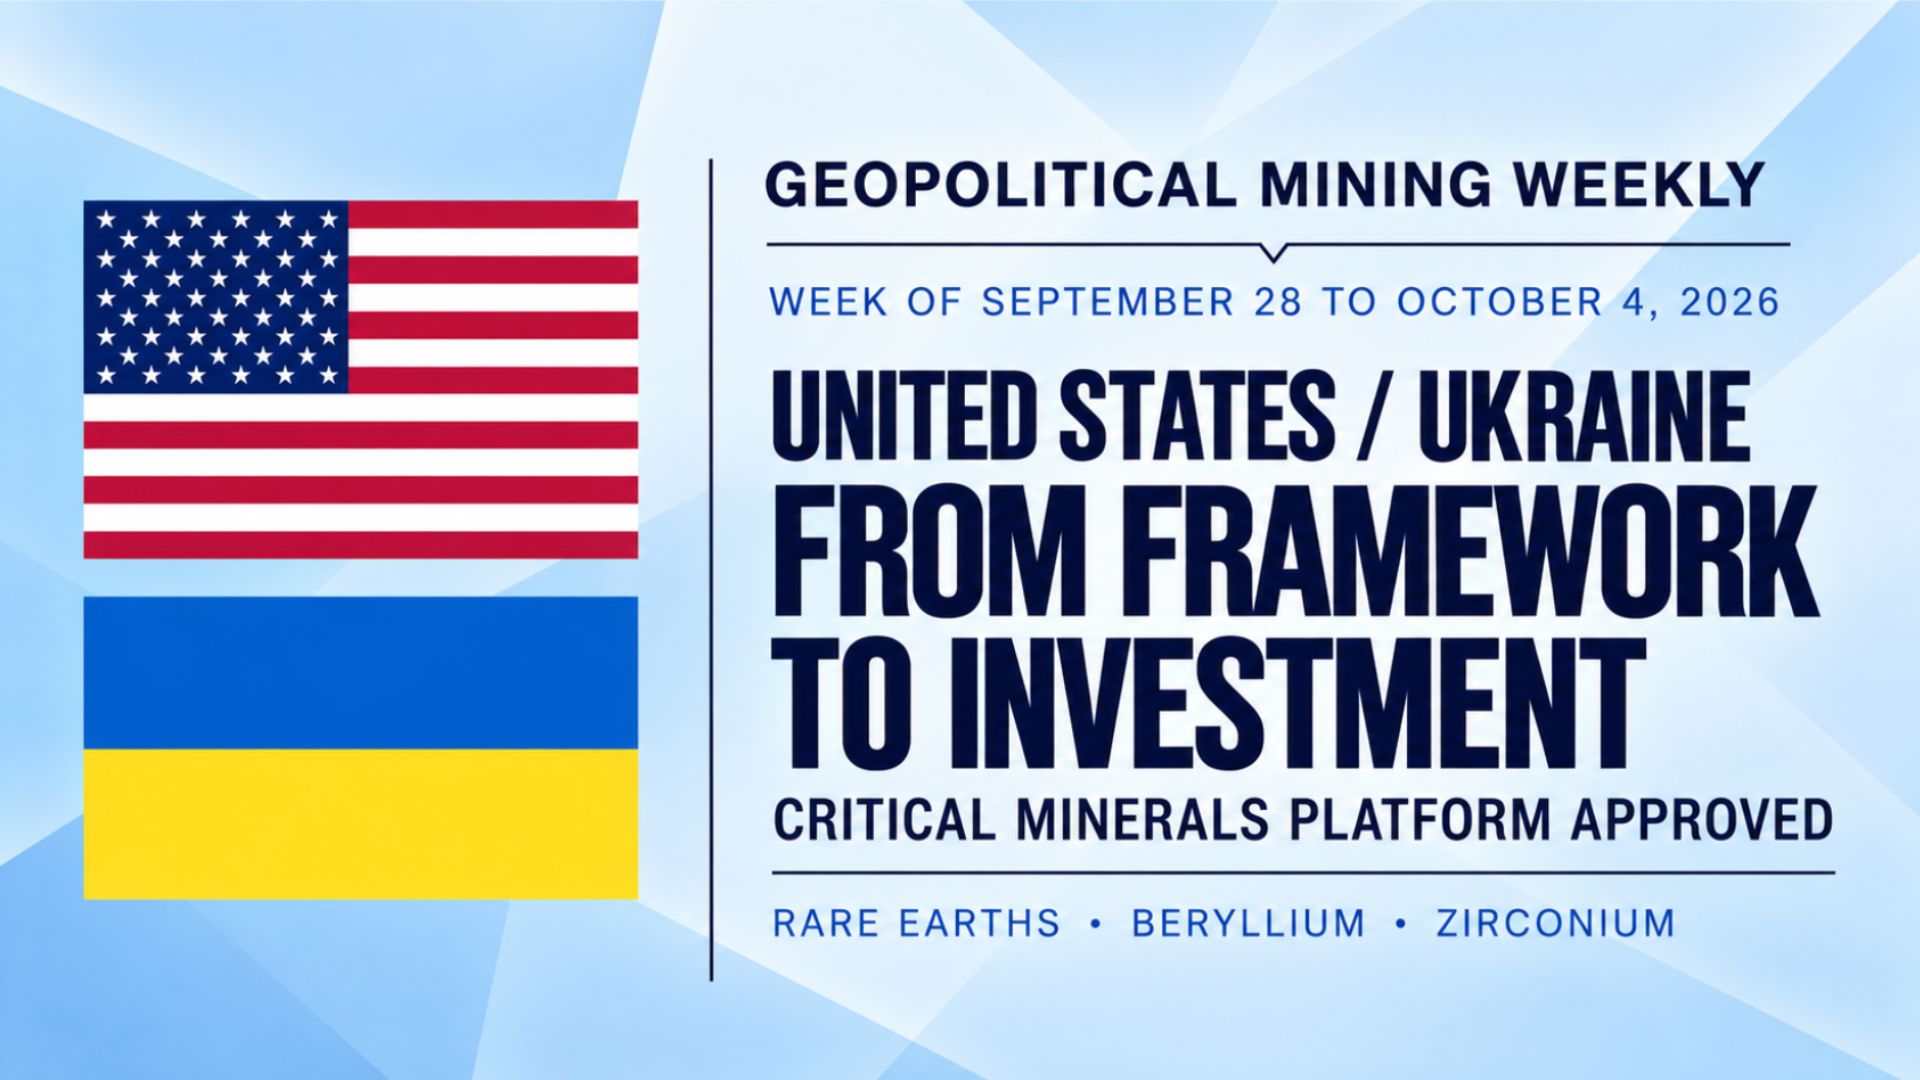
Geopolitical Mining Weekly · Week of September 28 to October 4, 2026
US Ukraine Critical Minerals Investment Platform Moves Into Project Origination
US Ukraine critical minerals moved into a new investment stage this week.
The Reconstruction Investment Fund approved a joint platform with BGV Group Management.
It will initially focus on identified rare earth, beryllium and zirconium assets in Ukraine.
Meanwhile, U.S. defense procurement became more specific.
A planned US$15 billion steel complex was linked to Minnesota iron ore.
Lynas and Meteoric signed a binding A$968 million transaction.
MARA received RIGI approval. Marathon entered construction.
Hope & Gorob began commercial concentrate production.
Cover Story · United States / Ukraine
US Ukraine critical minerals entered a new stage on October 2.
The Reconstruction Investment Fund board approved a joint investment platform
with BGV Group Management. The platform is intended to build a portfolio of
early stage mining projects in Ukraine. Its initial focus is on identified
rare earth, beryllium and zirconium assets.
However, Treasury did not disclose individual mine investments.
It also did not disclose project level capital commitments or construction decisions.
Those remain later steps.
What the board approved
The week in eight numbers
Industrial demand, ownership, capital and operating evidence
What this week says
Six readings from the week
State capital and procurement
US Ukraine Critical Minerals Enter Project Origination
Critical minerals move into project origination
The Reconstruction Investment Fund approved a platform with BGV Group Management. It will initially focus on rare earths, beryllium and zirconium assets. However, project level investment amounts remain undisclosed.
An actual delivery order was placed
DLA placed an initial US$125M delivery order. The five year contract has a maximum ceiling of US$995M. That ceiling is potential procurement, not money already ordered.
Strategic materials enter stockpile procurement
DLA awarded an approximately US$36M contract. It covers molybdenum and tungsten alloys and precision wire for the National Defense Stockpile.
National Laboratory projects enter award negotiations
DOE selected 17 projects for US$29.5M in award negotiations. The work includes rare earth processing and recovery from mine tailings.
Industrial demand and processing
Customers and downstream capacity became more visible
Planned steel capacity is linked to Minnesota iron ore
The announced Iowa complex is intended to use material from Mesabi Metallics. However, the steel plant remains planned. Mesabi is already in startup.
A future concentrate buyer is identified
Homeland Nickel and Westwin signed a binding Red Flat offtake. It contemplates about 20,000 tonnes of nickel concentrate a year. Studies, permitting and mine development still precede delivery.
New Amalga secures a seven year sales route
The definitive agreement can cover up to 100% of New Amalga production. That right applies during the first seven years of commercial operation.
Processing studies and pilot work receive funding
Tronox and JX Advanced Metals will jointly fund study and pilot work. The programme covers Australia and the United States. Commercial plants and proposed output remain future decisions.
Ownership and project pathways
Transactions and approvals changed who can advance major assets
Caldeira enters a binding acquisition process
Lynas and Meteoric signed a binding scheme implementation deed. However, the acquisition has not closed. Shareholder, court, regulatory and other conditions remain.
MARA gains access to the investment regime
RIGI approval gives MARA access to the regime’s fiscal and regulatory framework. However, it is not a final construction decision. MARA is not in production.
Cobre Panamá remains under preservation
The interministerial commission recommended evaluating a negotiated path. The report is advisory. Therefore, the President still retains final decision authority.
La Rosada can advance exploration work
Environmental approval authorizes the exploration programme. However, it does not authorize mine development or production.
Infrastructure before output
Power and access moved into place around mineral projects
Permanent power connection completed
Skouries completed its permanent connection to the Greek national grid. As a result, one defined infrastructure step is now complete.
Dedicated 33 kV line energised
Grid power is now available at site. Staged plant commissioning is planned for late November. Commercial rare earth production remains ahead.
Grid connection authorization confirmed
The project has authorization to connect to the El Lince line. It also has a preliminary renewable power framework. Construction and operating delivery remain later stages.
Webequie road construction manager appointed
Ontario and Webequie First Nation awarded the road construction manager contract. However, the award is not a mine approval.
Construction, commissioning and production
Physical execution crossed several distinct thresholds
Capital and operating continuity
Financing strength depended on legal stage and operating conditions
Credit approved underwriting commitment
KfW IPEX Bank and Société Générale reached the commitment stage. However, the full package has not closed. Financial close and FID remain ahead.
Definitive financing agreements signed
Atico signed a secured project finance facility. It also signed a convertible debenture arrangement. Drawdowns and closing remain subject to stated conditions.
Senior secured notes completed
Osisko Gold completed the notes offering. Proceeds are allocated to refinance project debt and advance Cariboo construction.
East Boulder gains labour continuity
Workers at East Boulder ratified a collective bargaining agreement through July 2029. Meanwhile, strike action continued at Stillwater East and the Columbus metallurgical facility.
Fenn Gib shows why financing labels matter
Mayfair Gold signed a C$10M equity subscription agreement. It also signed a nonbinding term sheet for a proposed C$300M project finance facility. Therefore, the C$310M headline should not be read as C$310M of closed financing.
Mining viability across the week
Strategy advanced through different legal and physical stages
The week ranged from an approved investment platform to actual procurement orders. It also included binding acquisitions, project approvals, construction and production. Meanwhile, Grasberg remained in operating recovery.
What follows
Dates and decisions already in view
Evidence from the Daily
Five editions behind this Weekly
Daily · September 29, 2026
United States · Iron Ore and Steel · US$15 Billion Iowa Plant Announced
Daily · September 30, 2026
United States · Specialty Steel · US$125 Million Initial Defense Order Placed
Daily · October 1, 2026
Panama · Copper · Cobre Panamá Negotiations Recommended
Daily · October 2, 2026
Australia / Brazil · Rare Earths · A$968 Million Acquisition Agreement Signed
Daily · October 3, 2026
Argentina · Copper · MARA Receives RIGI Approval
Selected official and primary sources
Documents behind the Weekly
The five Daily editions contain the complete source trail for the 30 developments. The sources below support the cover story. They also support the principal comparisons in this Weekly.
- U.S. Department of the Treasury U.S. Ukraine Reconstruction Investment Fund approvals Joint critical minerals platform with BGV Group Management and related energy investments.
- White House Planned Iowa steel complex and Minnesota iron ore linkage US$15B investment announcement and planned output.
- Metallus Defense Logistics Agency specialty steel contract US$125M initial delivery order and US$995M maximum contract ceiling.
- Meteoric Resources Binding Lynas acquisition scheme Caldeira transaction terms and approximately A$968M implied equity value.
- Generation Mining Marathon construction commencement Early works and construction phase financial assurance.
- Glencore MARA receives RIGI approval Investment regime approval and updated Alumbrera restart timing.
- Government of Panama Cobre Panamá final interministerial report Advisory recommendation to evaluate a negotiated path.
- Bezant Resources Hope & Gorob commercial production Commercial concentrate production commencement and ramp up status.
- Freeport McMoRan Grasberg third quarter operating update 67% average normalized mill throughput and recovery timetable.
- Tronox and JX Advanced Metals Rare earth processing cooperation and investment agreement US$32M for feasibility, pre feasibility and pilot work.
GM Signals provides the observation framework. The Daily records developments and their stage. The Weekly then compares the evidence. It identifies what changed across the mineral system.