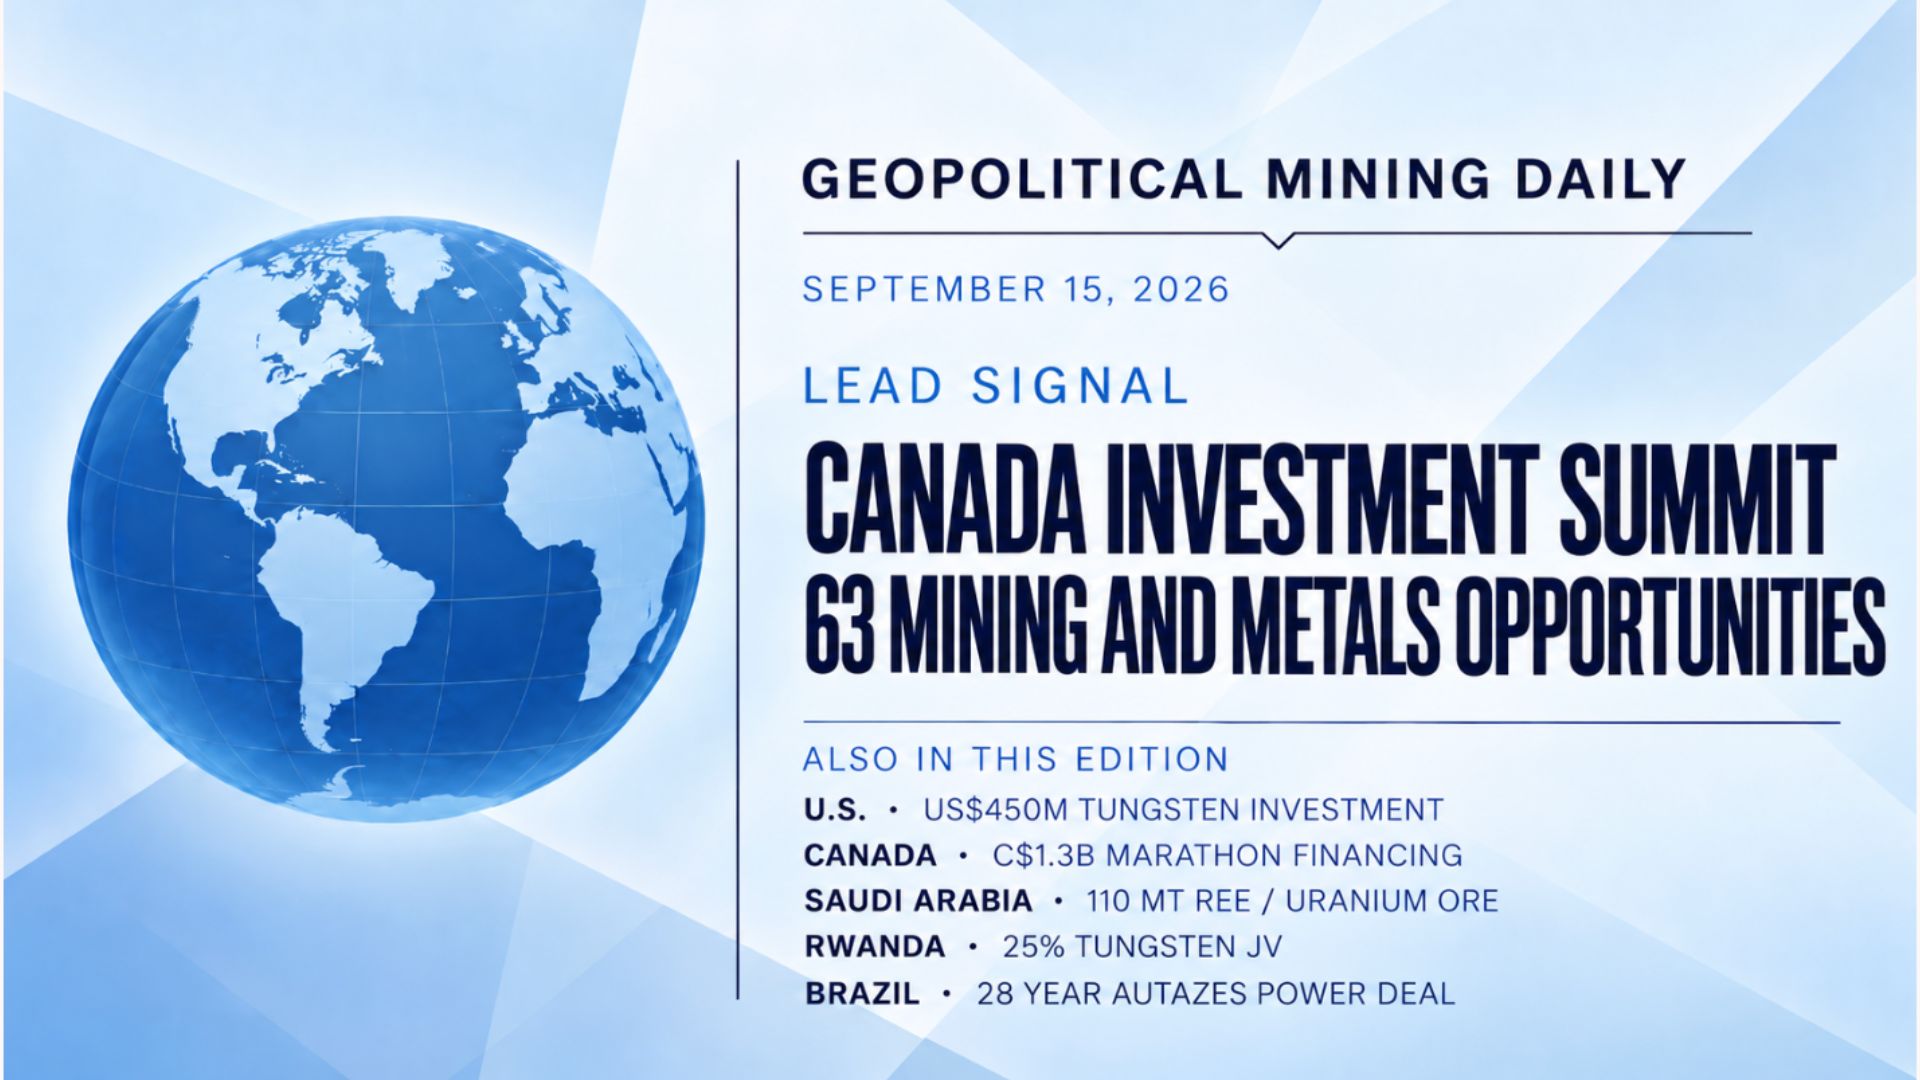
Geopolitical Mining Daily · September 15, 2026
Canada Investment Summit Showcases 63 Mining and Metals Opportunities
The Canada Investment Summit is placing mining and metals at the centre of Canada’s investment pitch, with 63 opportunities presented to global investors inside a broader C$1 trillion investment drive. The United States commits US$450 million to an integrated tungsten platform, Canada assembles Marathon’s construction financing, Saudi Arabia expands its strategic mineral inventory, Rwanda enters tungsten ownership and processing, and Brazil converts Autazes construction power into a definitive contract.
Canada opened the Canada Investment Summit with 167 investment opportunities, including 63 in Minerals and Metals, making the material base the largest category presented to global investors. The U.S. Department of War committed US$450 million to The Elmet Group to expand tungsten mining, processing and manufacturing. Generation Mining assembled the final C$340 million component of an approximately C$1.3 billion Marathon construction financing package. Saudi Arabia reported approximately 110 million tonnes of rare earth and uranium bearing ore at Jabal Sayid. Almonty and Rwanda signed a binding tungsten partnership with 25% government ownership. Brazil Potash converted a power MOU into a definitive 28 year Autazes agreement.
The 2026 observation framework
The ten Signals for 2026
Every Daily edition is read against the same ten strategic lenses. Signals activated by today’s verified developments are highlighted below.
Today’s direction of travel
The material economy is moving closer to the centre of national capital strategy. Canada is presenting mining and metals as its largest investment category, while the United States, Canadian public institutions, Saudi Arabia, Rwanda and Brazil are using equity, blended finance, geological inventory, ownership structures and infrastructure contracts to reduce different barriers between mineral potential and executable capacity.
Lead development
Canada Investment Summit puts 63 mining and metals opportunities before global capital
What happened
Canada opened the Canada Investment Summit in Toronto on September 14, bringing together global investors, Canadian chief executives and public sector representatives for a two day forum intended to accelerate long horizon investment into productive assets. The federal government says the summit forms part of a broader plan to catalyse C$1 trillion in total investment in Canada over five years and is hosted by Prime Minister Mark Carney in partnership with CPP Investments and PSP Investments.
The investment prospectus distributed for the summit contains 167 opportunities across eight sectors, including 63 in Minerals and Metals. That makes mining and metals the largest individual category by number of opportunities. Frontier Lithium, which confirmed inclusion of its PAK Lithium Project on September 14, said the prospectus places those 63 projects alongside opportunities in clean energy, infrastructure, advanced manufacturing, digital technology and other sectors.
The summit is being accompanied by attempts to strengthen the capital environment around those opportunities. TD announced a five year C$150 billion commitment covering new lending, underwriting, advisory and other financing activities across sectors including critical minerals and resources. Inclusion in the summit prospectus does not constitute project financing, government approval or a Final Investment Decision. Its significance is that Canada is deliberately placing mines, processing projects and metals opportunities in front of institutional capital as part of a national investment strategy.
Signal reading
The material base is becoming part of Canada’s investment architecture rather than sitting only inside natural resource policy. The relevant strategic change is the connection being attempted between mineral endowment, large project pipelines, institutional investors and financing capacity. The prospectus creates visibility and prioritisation, while the proof of execution will come from whether projects move into due diligence, binding capital, offtake, construction and production.
Next proof point: evidence that summit exposure converts into formal due diligence, financing mandates, strategic partnerships, offtake agreements, binding capital commitments, construction decisions and measurable advancement across the mining and metals portfolio.
Government and primary company sources
Government of Canada: Canada Investment Summit 2026, C$1 trillion investment objective and summit structure.Frontier Lithium primary company distribution: 167 summit opportunities including 63 in Minerals and Metals.
TD Bank Group: five year C$150 billion commitment including critical minerals and resources.
Major development
U.S. commits US$450 million to Elmet tungsten supply chain
What happened
On September 14, the United States Department of War announced a US$450 million redeemable preferred equity investment in The Elmet Group through the Industrial Base Analysis and Sustainment program. Elmet describes the package as a committed investment, with an initial US$200 million drawdown expected at closing and additional drawdowns thereafter. The structure therefore establishes a large public capital commitment while leaving the timing of the full cash deployment tied to closing and subsequent funding steps.
Elmet plans to direct more than US$165 million to manufacturing facilities in Maine, Michigan and Ohio, and approximately US$150 million to the Springer Tungsten Complex in Nevada through a majority owned joint venture with Blue Moon Metals and EQ Resources. The Springer plan is intended to restart and expand ammonium paratungstate conversion capacity. Elmet also plans a new refining and trading division to coordinate sourcing, refining and delivery across United States and allied supply routes.
Separately, Elmet Technologies received an indefinite delivery, indefinite quantity contract from the Defense Logistics Agency for tungsten ores, concentrates and sodium tungstate. The contract has a ceiling of up to US$2 billion and a guaranteed funded commitment of US$150 million. The ceiling should therefore be read as potential procurement capacity rather than as US$2 billion already committed for delivery.
Signal reading
The United States is linking public equity, domestic manufacturing, mine restart, APT conversion and strategic stockpiling inside one tungsten architecture. The significance lies in the attempt to close several interfaces at once: raw material access, chemical conversion, component manufacturing and government demand. Execution now moves to capital drawdown, physical expansion and contracted deliveries rather than policy design alone.
Next proof point: closing and the first US$200 million drawdown, formation and funding of the Springer joint venture, restart and expansion of APT conversion, execution of the manufacturing upgrades, additional investment drawdowns and the first deliveries under the DLA stockpile contract.
Major development
Generation Mining assembles C$1.3 billion Marathon construction financing package
What happened
Generation Mining announced C$340 million of final funding required to complete the financing package for its 100% owned Marathon Copper Palladium Project in northwestern Ontario. The new component consists of a C$200 million bought deal, a C$40 million private placement by Canada Growth Fund and C$100 million of subordinated unsecured convertible notes split equally between Canada Growth Fund and Canada Infrastructure Bank.
Combined with previously announced senior secured debt, subordinated debt, the undrawn portion of the metal stream and estimated equipment leasing, the company says it has arranged an approximately C$1.3 billion fully financed construction package. The package includes a C$185 million cost overrun facility in addition to the contingency embedded in the project capital estimate.
Glencore has also agreed to terms for an offtake arrangement covering polymetallic copper concentrate from Marathon. The material is intended to support domestic value added processing at the Horne smelter in Québec and the CCR refinery. Several financing components still require closings, regulatory or shareholder approvals, definitive documentation and satisfaction of conditions. Generation expects its board to consider a final investment decision after completion of all final funding components.
Signal reading
Marathon has crossed from a project seeking a finance solution into one with the complete financing stack assembled on announced terms. The composition matters as much as the headline total: federal investment vehicles are absorbing part of the capital requirement while private lenders, equity investors, streaming capital and Glencore connect construction finance to a domestic processing route. The remaining distinction is between financing arranged and financing closed.
Next proof point: closing of the bought deal, private placement and convertible notes, required shareholder and exchange approvals, completion of remaining financing documentation, the board final investment decision and commencement of early works targeted for the fourth quarter of 2026.
Strategic development
Saudi Arabia reports about 110 million tonnes of rare earth and uranium bearing ore at Jabal Sayid
What happened
Saudi Energy Minister Prince Abdulaziz bin Salman told the International Atomic Energy Agency General Conference that exploration and geological studies at the Jabal Sayid project in Madinah had identified estimated resources of approximately 110 million tonnes of ore containing high concentrations of rare earth minerals, particularly heavy rare earth elements, together with promising uranium concentrations.
The public announcement expands the mineral context around Saudi Arabia’s wider energy and industrial strategy, but it does not disclose rare earth or uranium grades, contained metal quantities, recovery assumptions, a formal reserve statement or project economics. The 110 million tonne figure refers to mineralized ore, not to 110 million tonnes of rare earths or uranium.
The minister placed the work inside Saudi Arabia’s effort to explore domestic uranium resources and develop rare earth discoveries into economic value. Further technical disclosure will be required before the scale of recoverable material or a development pathway can be assessed.
Signal reading
The announcement adds potentially large geological optionality in two strategically sensitive mineral groups at a time when Saudi Arabia is seeking a broader role in energy and materials. Its importance today is geological and strategic rather than productive. The conversion test begins with grade, mineralogy, metallurgy, ownership, permitting and economics before any supply contribution can be measured.
Next proof point: a technical resource statement with grades and contained quantities, mineralogical and metallurgical results, clarification of project ownership and licensing, a development concept, environmental and regulatory pathways and economic studies capable of testing recoverability.
Direct government source
Saudi Press Agency: Kingdom statement at the 70th IAEA General Conference.Major development
Almonty and Rwanda create a tungsten platform with 25% government ownership
What happened
Almonty Industries announced a binding agreement with the Government of Rwanda under which the government will receive a 25% interest in Almonty Rwanda Pty Ltd and Almonty will retain 75%. The government interest is being provided in exchange for contribution of the approximately 32 square kilometre Shyorongi tungsten exploration concession and a mineral processing licence for a mobile tailings processing unit.
The structure is designed to access material from Rwanda’s existing mining base before a new mine is developed. Almonty Rwanda may acquire ore, preconcentrate and panning tailings from licensed operators, including small scale producers, for sale or upgrading. A mobile processing unit is intended to operate near existing tailings areas while exploration advances at Shyorongi.
A centralized collection and processing plant is contemplated as a later stage and remains subject to a separate binding investment and development agreement. The partnership followed an introduction by the United States Department of State under the 2025 U.S. Rwanda Framework for Shared Economic Prosperity.
Signal reading
Rwanda is entering the ownership structure while contributing mineral rights and processing authority, and Almonty is connecting existing production, tailings, exploration and future processing in one platform. This gives the arrangement a shorter pathway to material flows than a conventional greenfield exploration project, while leaving the centralized plant and broader development framework for a subsequent agreement.
Next proof point: completion of the equity and asset contribution steps, commercial agreements with local licence holders, acquisition and permitting of the mobile processing unit, first collection and export or upgrading of material, exploration results at Shyorongi and a separate binding agreement for the centralized processing plant.
Company release distributed through Business Wire
Almonty Industries: binding Rwanda tungsten partnership and transaction terms.Infrastructure development
Brazil Potash converts Autazes power MOU into a definitive 28 year contract
What happened
Brazil Potash announced that its wholly owned subsidiary Potássio do Brasil signed a definitive agreement with Gera Center for implementation, operation and maintenance of a modular power plant for the Autazes Potash Project. The agreement replaces the nonbinding memorandum announced in May and has a 28 year term: five years supplying construction power followed by 23 years as backup power after the mine enters operation.
Under the Build Own Operate structure, Gera Center will fund, build, own and operate 45 modular diesel generators with peak capacity of 20 megawatts. Initial capacity is planned at 10 megawatts, increasing to 20 megawatts during the first year. Initial mobilization is expected within 120 days after Brazil Potash issues an Order to Proceed.
The company estimates that the structure removes approximately US$33 million of power related spending from the upfront construction budget and produces approximately US$10 million of net savings over the contract life compared with earlier estimates. The project site still lacks a connection to Brazil’s national grid, and the modular plant is intended to support shaft, processing plant and port construction until the planned transmission connection is completed.
Signal reading
Autazes has converted a preliminary infrastructure concept into a long duration contractual arrangement that transfers a specific capital requirement to a specialist provider. That improves construction readiness and reduces upfront funding pressure, while the mine itself still depends on broader project finance, construction execution and the eventual grid connection.
Next proof point: issuance of the Order to Proceed, mobilization within the stated 120 day window, installation and commissioning of the modular plant, completion of the wider construction financing package, progress on shafts and processing facilities and eventual connection to the national grid.
Direct company source
Brazil Potash: definitive 28 year construction and backup power agreement.The system reading
What today’s evidence tells us
Today’s evidence shows mineral strategy being organised through the mechanisms that determine whether projects can attract capital and become physical supply. Canada is putting 63 mining and metals opportunities directly in front of global investors, but inclusion in a summit prospectus is still exposure rather than financing. The United States has committed public equity to an integrated tungsten platform, while the full capital will be drawn through execution stages. Marathon has assembled an approximately C$1.3 billion construction financing package, while final closings and board FID remain ahead. Saudi Arabia has disclosed geological scale without yet publishing the grades, contained metal or economics required for a mine. Rwanda has a binding ownership and processing platform, while larger central processing requires further agreement. Autazes has converted construction power from an MOU into a definitive contract, but the broader project still depends on financing and construction. Across all six developments, the direction is clear: mineral power increasingly depends on the quality of the institutional, capital and infrastructure architecture surrounding the resource.
Signals for 2026 gives the map. The Daily records new evidence against that map. Today’s lead shows Canada positioning mining and metals inside a national investment strategy, while the wider edition follows state equity, project finance, geological inventory, ownership and processing rights, and infrastructure contracts across five additional jurisdictions.